Newsletter
CORRECTION: Income Investing With Infrastructure Capital
A Lead-Lag Live CE Credit Webinar • June 4, 2026 • 2:00 PM ET
Newsletter
A Lead-Lag Live CE Credit Webinar • June 4, 2026 • 2:00 PM ET
Leaders-Laggards
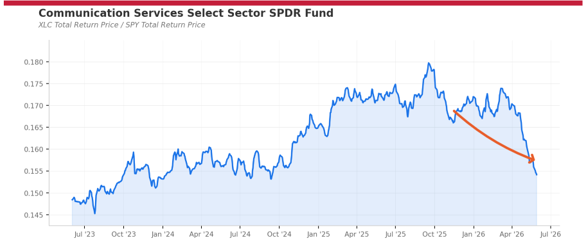
S&P +1.5% On Week 9; XLK +5.9% On NVDA Beat; XLE -5.4% Flips To Laggard On Iran Ceasefire; 10Y Softens To 4.45%; EEM Leads All Major Indexes
Weekly Signals
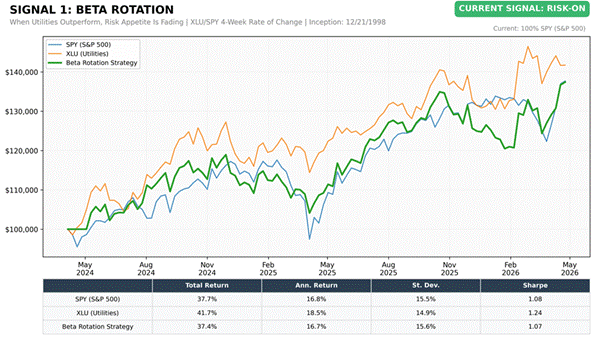
Three of four signals favor risk-on positioning, though one holdout warrants attention.
Newsletter
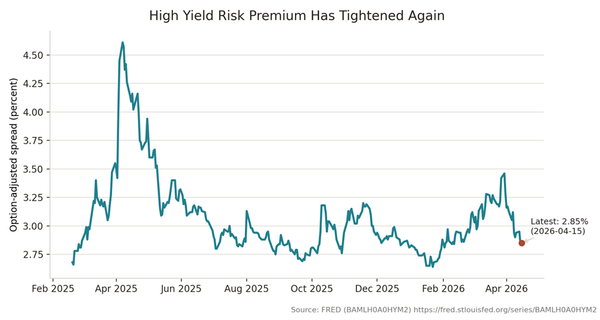
KEY HIGHLIGHTS · High yield’s risk premium has compressed back toward cycle lows, with the ICE BofA US High Yield Option-Adjusted Spread at **2.85% (Apr 15, 2026)**.[1] · The yield curve remains positively sloped, with the 10-year minus 2-year Treasury spread at **0.53% (Apr 15,
Closing Thoughts for the Week
When does record euphoria become a setup, not a celebration?
Macro Observations
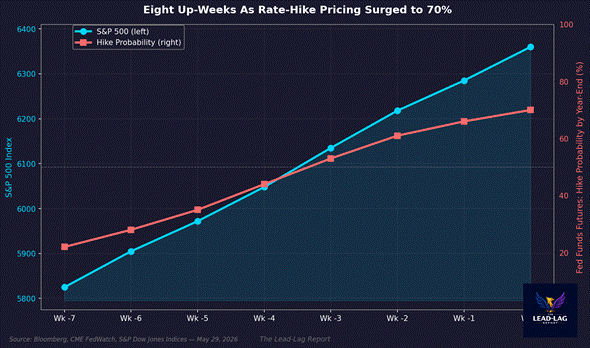
Markets just priced 70% odds of a Fed HIKE — and ran eight straight up-weeks anyway. The duration playbook just broke.
Newsletter
The AI conversation has fixated on the same six names for two years. Matt Tuttle thinks the more interesting layer sits one step beneath the hyperscalers — in the **physical infrastructure** that AI cannot exist without. On Monday, June 1 at 2:00 PM ET, Matt joins the Lead-Lag team
Macro Observations
If you missed a few paywalled pieces this month, here are 3 from the archive worth your time. Two cities, two nights, last seats — Boston tomorrow, NYC ThursdayIf you have been wondering why equities can rally even as rate expectations rise, this frames the positioning setup and the risk signal
High Yield Spotlight
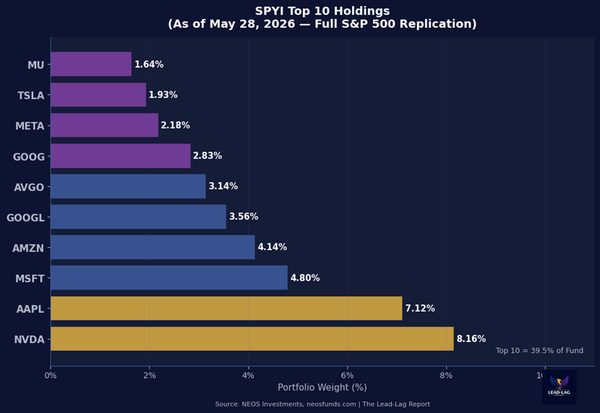
NEOS S&P 500 High Income ETF (CBOE: SPYI) — $10 Billion in Assets, 12% Yield, and a Tax Structure That Changes the Income Equation

Global View
Dow 50,000. Nikkei 65,000. KOSPI 8,000. NVDA prints the best quarter in semiconductor history — and U.S. jets struck Iran, Bitcoin ETF flows went sharply negative, and gold confirmed a 15% correction.
Newsletter
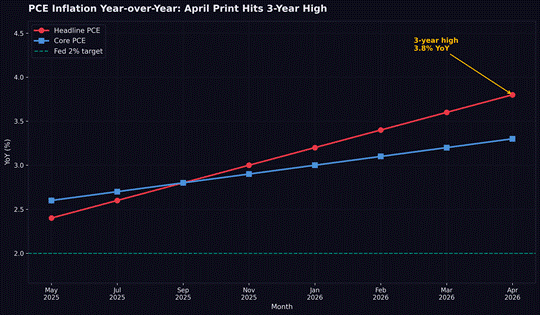
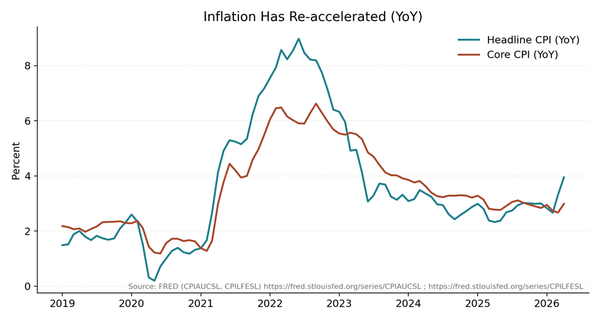
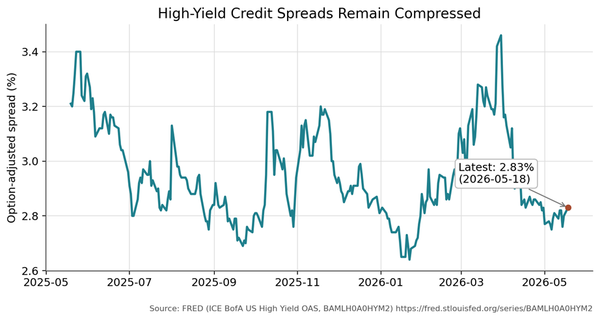
KEY HIGHLIGHTS · **April CPI rose 0.6% m/m and 3.8% y/y**, while **core CPI rose 0.4% m/m and 2.8% y/y** — a mix that keeps policy uncertainty elevated.[1] · **High yield option-adjusted spreads sit near 2.82%** (latest), a level that implies credit
Newsletter
KEY HIGHLIGHTS · **Headline CPI rose 0.6% m/m and 3.8% y/y in April**, while **core CPI rose 0.4% m/m and 2.8% y/y**—a reminder that inflation volatility is back in the driver’s seat.[1] · The **10Y–2Y Treasury spread is back to