Tech Extremes as the Fed Hikes: XLK/SPY Hits +2.65 Sigma, Framework Streak Reaches Week 6, Credit Holds
XLK/SPY at +2.65 sigma, XLU/SPY at -3.01 in Week 6 of the deeply broken framework, credit confirms risk appetite as the Fed hikes into tech strength
Today’s Lead-Lag Report post is sponsored by GraniteShares
MVLL seeks 2x (200%) the daily percentage change of Marvell Technology, Inc. (MRVL), via swap-based exposure, single-ticker, single-day. A 2x-magnified expression of a directional view on MRVL, without options.
Daily reset. Not a buy-and-hold investment. Intended for active traders holding for very short periods, often a single trading day. Investors could lose the full value of their investment within a single day. Please read the prospectus.
Book a walk-through with GraniteShares
Fund page + prospectus
This material must be preceded or accompanied by a Prospectus. Investment in the Fund involves risk, including possible loss of principal. Not suitable for all investors; daily reset; short-holding-period tool.
The Fund is distributed by ALPS Distributors, Inc. GraniteShares is not affiliated with ALPS Distributors, Inc.
SSC Approval ID: GRS002576
DISCLAIMER – PLEASE READ: This is sponsored advertising content for which Lead-Lag Publishing, LLC has been paid a fee. The information provided in the link is solely the creation of GraniteShares. Lead-Lag Publishing, LLC does not guarantee the accuracy or completeness of the information provided in the link or make any representation as to its quality. All statements and expressions provided in the link are the sole opinion of GraniteShares. and Lead-Lag Publishing, LLC expressly disclaims any responsibility for action taken in connection with the information provided in the link.
Tech Extremes as the Fed Hikes: XLK/SPY Hits +2.65 Sigma, Framework Streak Reaches Week 6, Credit Holds
XLK/SPY at +2.65 sigma, XLU/SPY at -3.01 in Week 6 of the deeply broken framework, credit confirms risk appetite as the Fed hikes into tech strength
Previously on Leaders-Laggards
Scoring note: the Run #29 forward-call ledger was lost in the platform migration that moved this column to the role-home architecture, and the forward-call scorecard cron holds the canonical scoring until the ledger is reseeded. Nothing in this section is scored from memory. What is verifiable from the Run #29 edition snapshot against Friday's close, computed from yfinance daily closes through September 18, 2026:
- Lumber/Gold, Run #29's headline at -2.16 sigma Extreme, now reads -1.36 sigma Notable, with the month still -5.1%. The extreme partially normalized; the trend did not reverse. [PENDING]
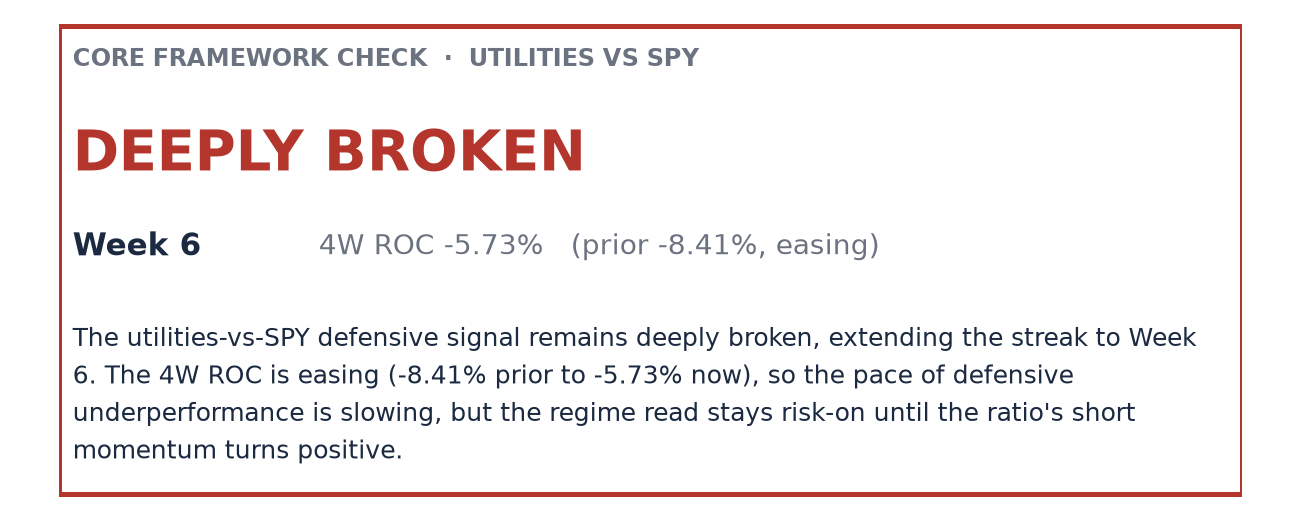
- The core framework check extended from DEEPLY BROKEN Week 5 at a -8.41% 4W ROC to Week 6 at -5.73%. [PENDING]
- Energy, recorded in Run #29 as consolidating leadership, printed +17.3% over the trailing three months. [PENDING]
Streak tracking, verified against the computed series:
- XLU/SPY: DEEPLY BROKEN extended Week 5 to Week 6; 4W ROC -8.41% to -5.73%, easing.
- Lumber/Gold: -2.16 sigma Extreme to -1.36 sigma Notable; extreme resolved, direction intact, 1M -5.1%.
- JNK/GOVT: confirming streak held through a Fed hike and a BOJ hike; +1.38 sigma, no negative month.
- TLT/SPY: laggard streak extended; -1.64 sigma, 1Y -22.0%.
Leaders: Ratios Where the Denominator Is Losing
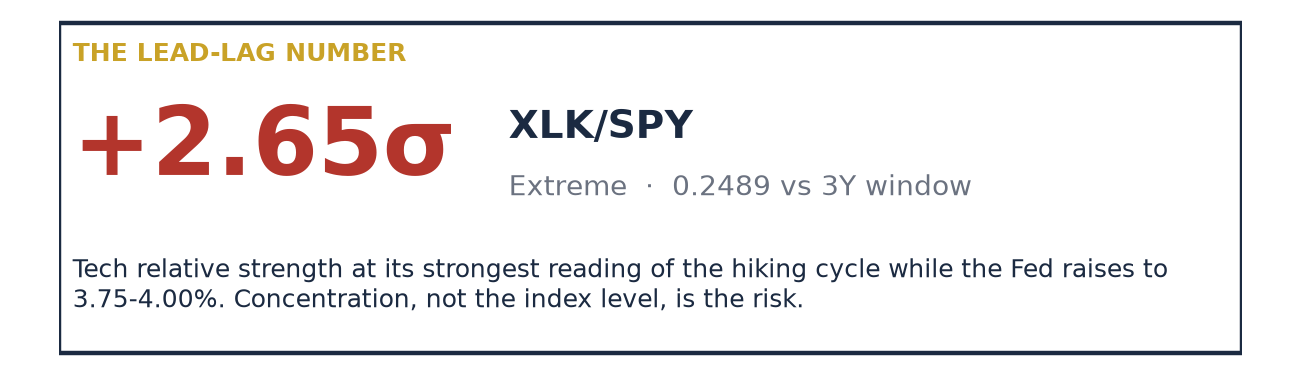
XLK/SPY: Signal strength +2.65σ Extreme · RRG: leading
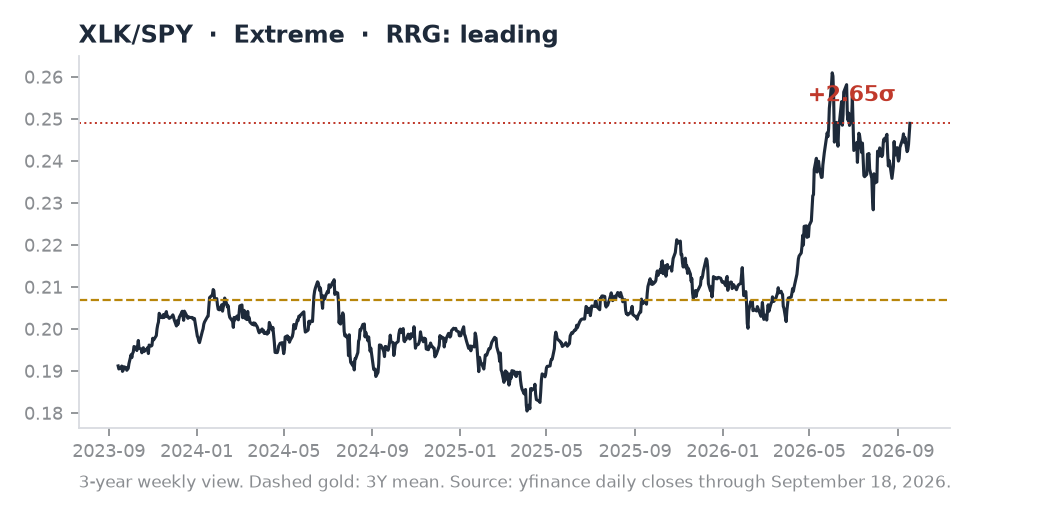
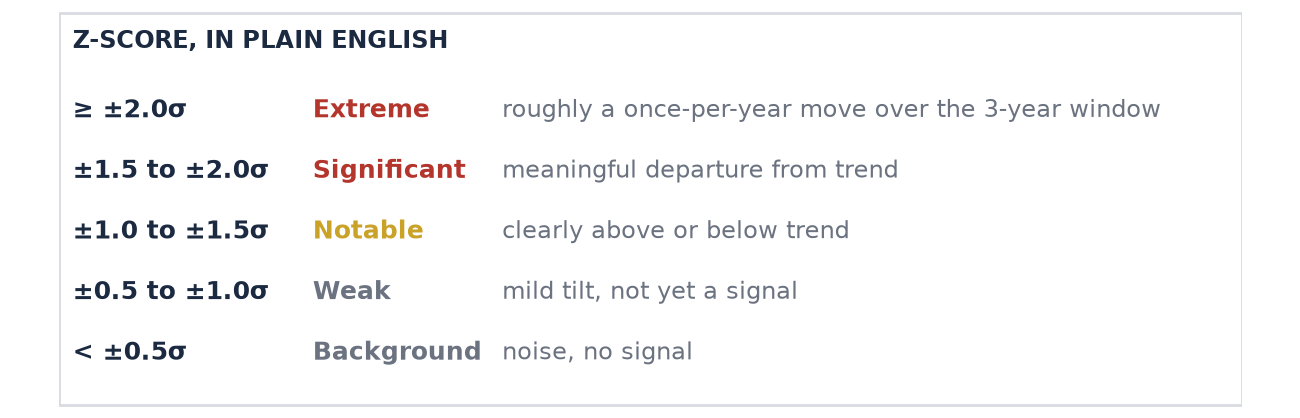
Plain-English: a extreme departure from its 3-year trend, roughly a once-per-year class move at this reading.
Returns: 1M +4.2% · 3M -2.9% · 6M +18.6% · 1Y +20.9%
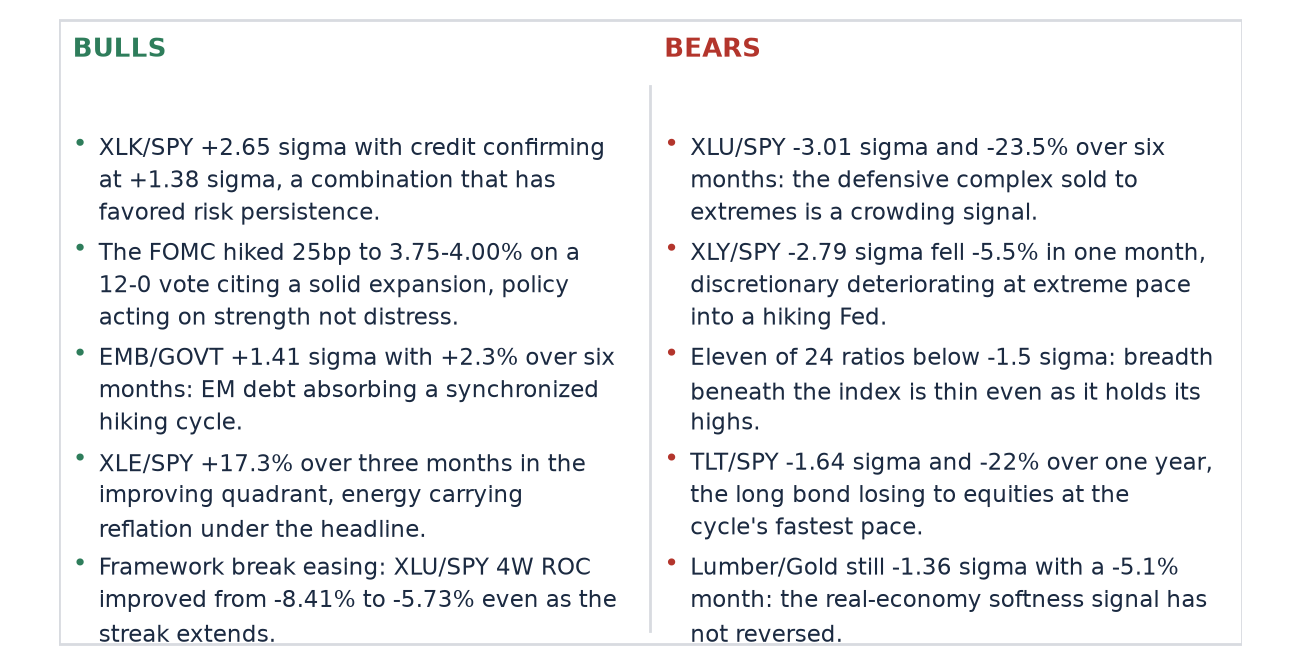
Tech extended its leadership to the strongest reading of the hiking cycle, +2.65 sigma, with a +4.2% month while the Fed was actively raising. The FOMC's September statement leaned on productivity and capital investment as its cover for tightening, and both arguments are tech-adjacent. The risk in this reading is arithmetic: the ratio's 3-year mean sits far below the current level, and mean reversion from extreme does not require a catalyst, only time. The confirmation to demand is a second positive month; extremes unwind slowly and then suddenly.
EMB/GOVT: Signal strength +1.41σ Notable · RRG: leading
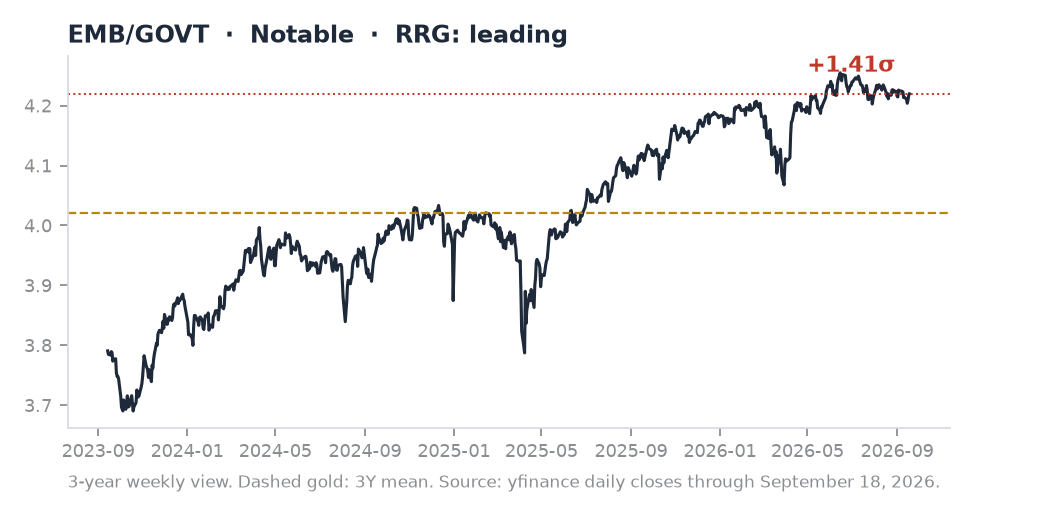
Plain-English: a notable departure from its 3-year trend, roughly clearly above or below trend at this reading.
Returns: 1M +0.0% · 3M -0.8% · 6M +2.3% · 1Y +2.4%
Emerging-market dollar debt outperformed Treasuries again, +1.41 sigma, absorbing a global hiking cycle that now includes a Bank of Japan hike to 1.25%, a 31-year high, on a 7-2 vote. Sovereign spread behavior under synchronized tightening is the cleanest available read on real-economy stress, and there is none in this series yet. The reading carries the same caution as every other extreme-adjacent leader: it is evidence of resilience, not a promise of continuation.
JNK/GOVT: Signal strength +1.38σ Notable · RRG: leading
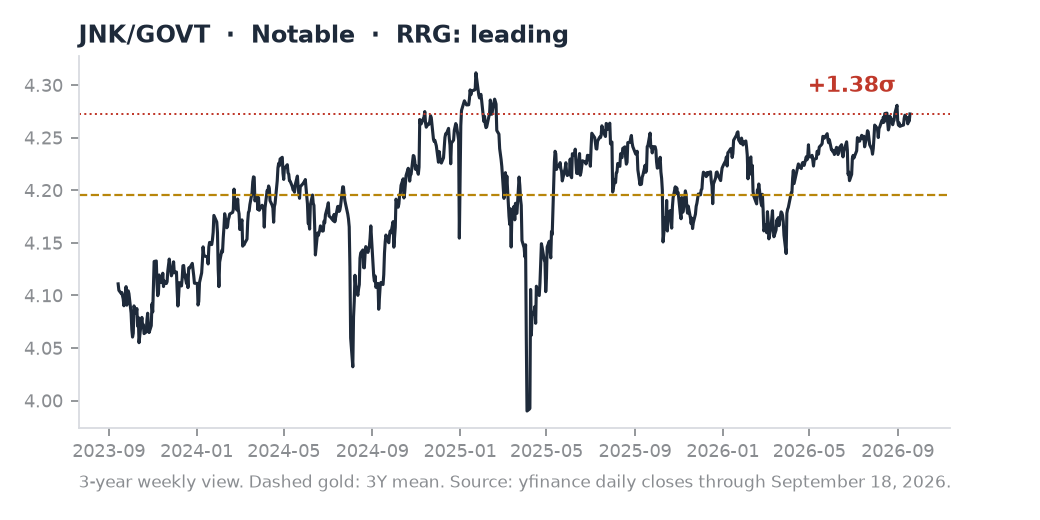
Plain-English: a notable departure from its 3-year trend, roughly clearly above or below trend at this reading.
Returns: 1M +0.4% · 3M +0.8% · 6M +2.4% · 1Y +1.3%
High yield confirmed for another week at +1.38 sigma. Credit is the confirming vote on every risk signal in this edition, and it voted with the bulls: +0.4% on the month against Treasuries, +1.3% over a year in which the Fed raised three times. The specific flip condition stays the same, one clean negative month, and until it arrives, the risk-on framework read holds.
EEM/SPY: Signal strength +1.27σ Notable · RRG: leading
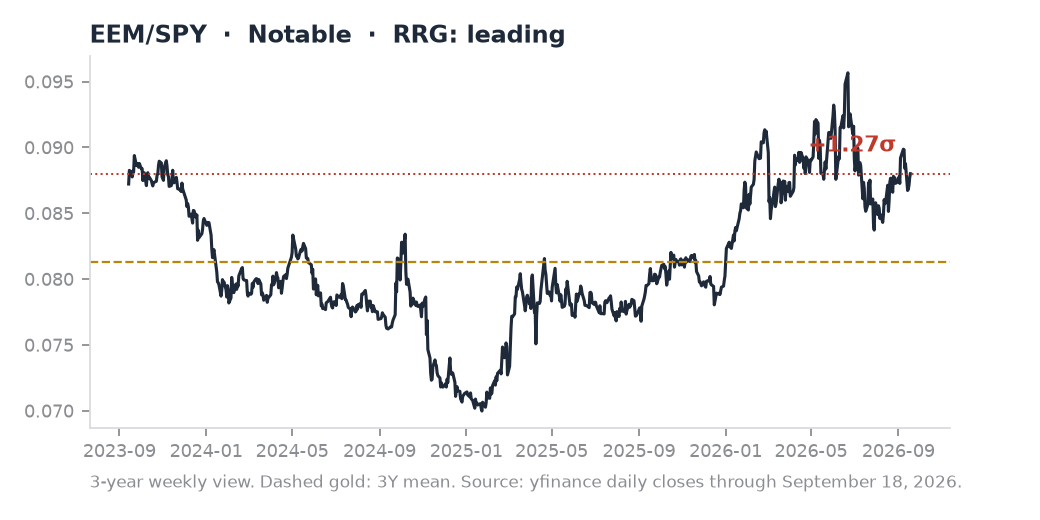
Plain-English: a notable departure from its 3-year trend, roughly clearly above or below trend at this reading.
Returns: 1M +2.4% · 3M -7.2% · 6M +0.8% · 1Y +8.9%
Emerging-market equities outperformed the S&P for a second week at +1.27 sigma, +2.4% on the month even after -7.2% over three. The pairing with EMB/GOVT matters: both legs of the EM complex, equities and sovereign debt, are on the right side of the ledger simultaneously. That combination argues the outperformance is a repositioning trend rather than a bounce.
EUFN/SPY: Signal strength +1.18σ Notable · RRG: leading
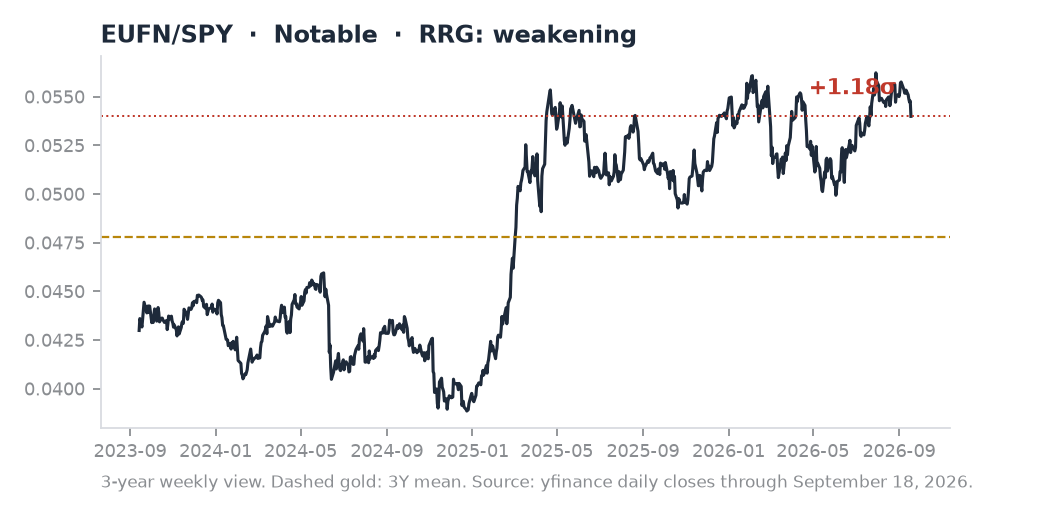
Plain-English: a notable departure from its 3-year trend, roughly clearly above or below trend at this reading.
Returns: 1M -1.0% · 3M +4.1% · 6M +4.0% · 1Y +4.8%
European financials held +1.18 sigma. The sector's relative strength through a BOJ hike to 1.25% and a Fed hike to 3.75-4.00% is the quiet structural argument in this edition: banks are the beneficiaries of the steeper curves the hikes produce, and the ratio's +4.8% year says the market has been pricing exactly that.
XLE/SPY: Signal strength +0.49σ Background · RRG: improving
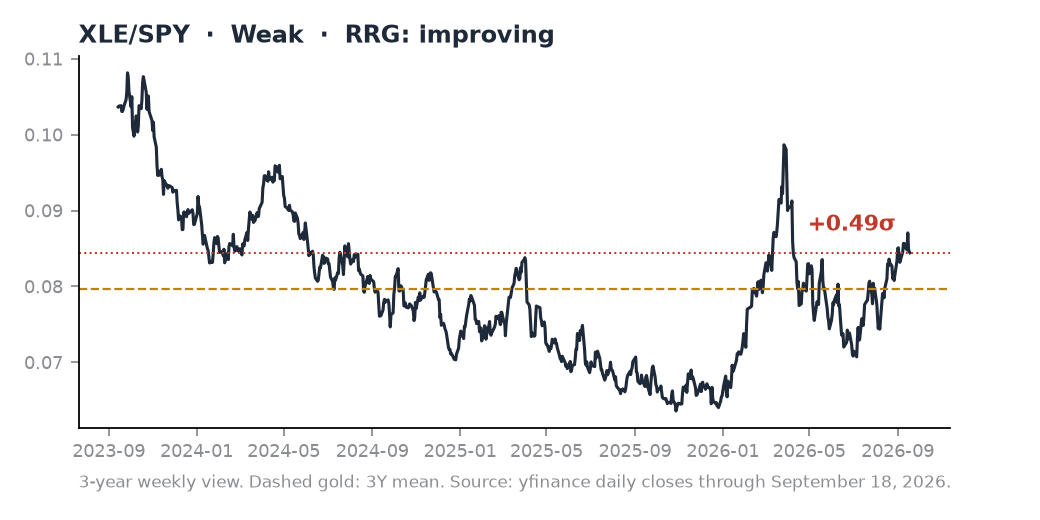
Plain-English: a background departure from its 3-year trend, roughly a mild tilt at this reading.
Returns: 1M +2.1% · 3M +17.3% · 6M -6.2% · 1Y +23.7%
Energy sits at +0.49 sigma, background-band but improving, with +17.3% over three months and +23.7% over the year. The quadrant shift matters more than the level: energy has cycled from laggard to leader to consolidating leader across recent editions, and its improvement beneath the tech headline is the reflation argument still being carried.
GLD/SPY: Signal strength +0.50σ Weak · RRG: improving
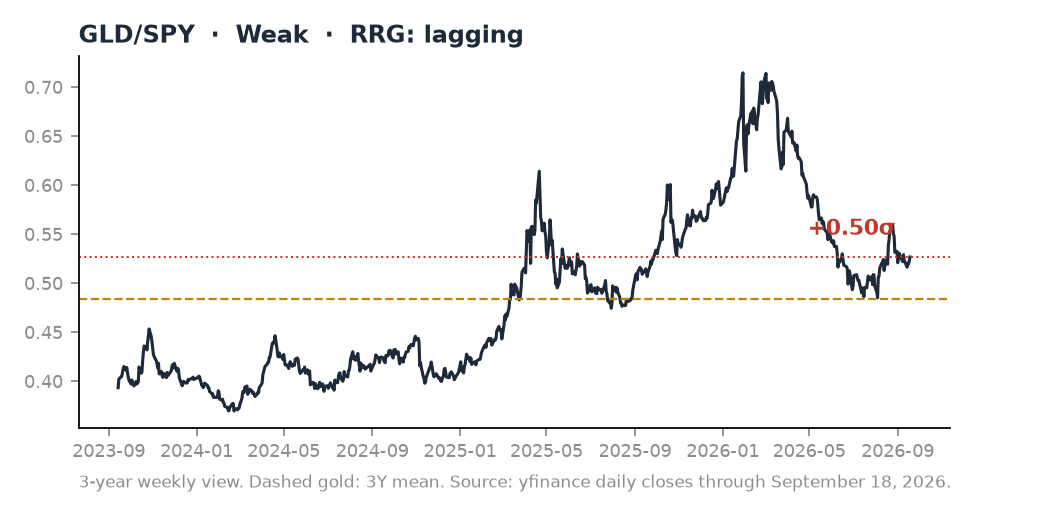
Plain-English: a weak departure from its 3-year trend, roughly a mild tilt at this reading.
Returns: 1M -2.1% · 3M +1.6% · 6M -18.5% · 1Y +3.0%
Gold slipped -2.1% on the month to +0.50 sigma, background band. The metal's -18.5% six-month reading against equities is the largest mid-range divergence in the table, and its recent stabilization is worth a footnote rather than a section: real rates rising with a Fed promising to deliver price stability is the headwind, and it has not cleared.
Credit Confirmation: JNK/GOVT
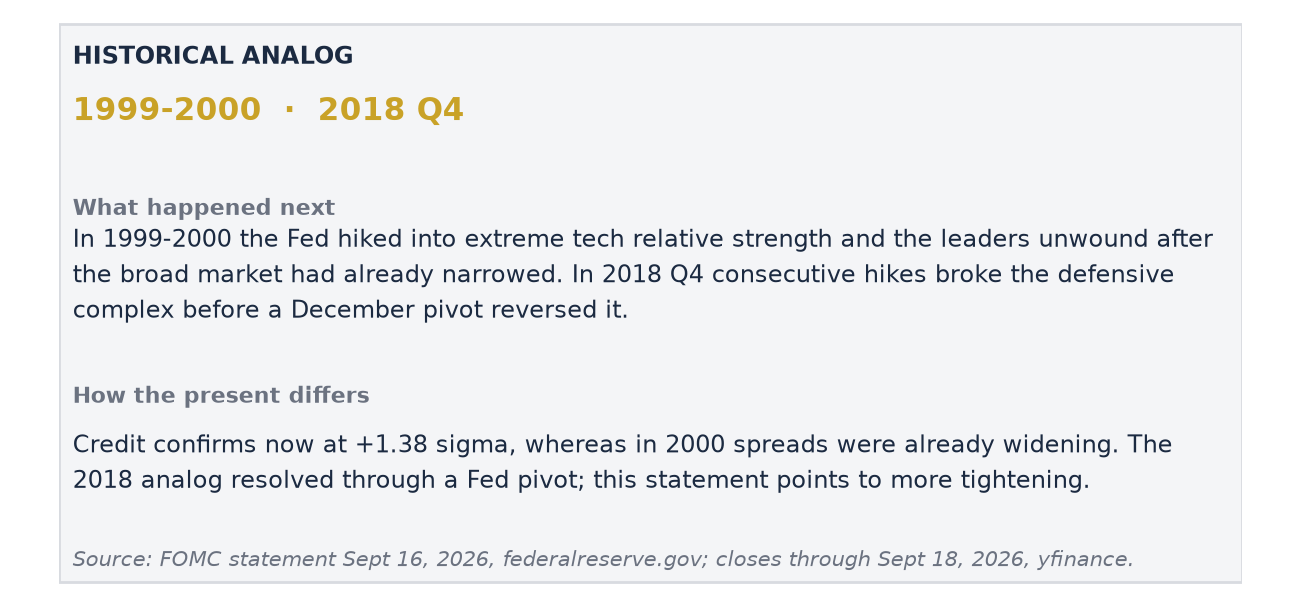
Credit confirms. JNK/GOVT printed +1.38 sigma, +0.4% on the month, through a week containing a 25 basis point Fed hike to a 3.75-4.00% target range on a 12-0 vote and a Bank of Japan hike to 1.25%, both per the respective central bank announcements. High yield absorbed both without a wobble, and every risk signal above stands on that confirmation. The flip condition is specific: one clean negative month in JNK/GOVT while XLU/SPY attempts a base would move credit from confirming to disconfirming, and that combination, not the Fed's next move, is the thing that ends this regime read.
Laggards: Ratios Where the Denominator Is Winning
XLU/SPY: Signal strength -3.01σ Extreme · RRG: lagging
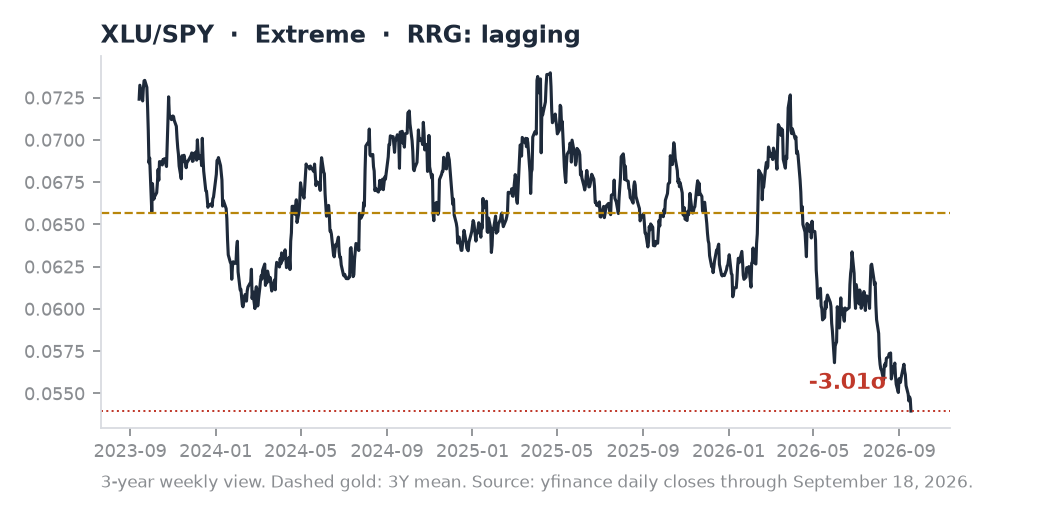
Plain-English: a extreme departure from its 3-year trend, roughly a once-per-year class move at this reading.
Returns: 1M -5.7% · 3M -10.0% · 6M -23.5% · 1Y -15.7%
The framework pair itself is the extreme of the week on the downside: -3.01 sigma, -5.7% on the month, -23.5% over six months. This is the sixth week of the deeply broken reading, and the detail that matters is the easing pace: the 4W ROC improved from -8.41% to -5.73%, deterioration decelerating. The streak ages when the rate of change turns, not when the level does, and the level is still the most extreme reading in either direction on the board.
XLY/SPY: Signal strength -2.79σ Extreme · RRG: lagging
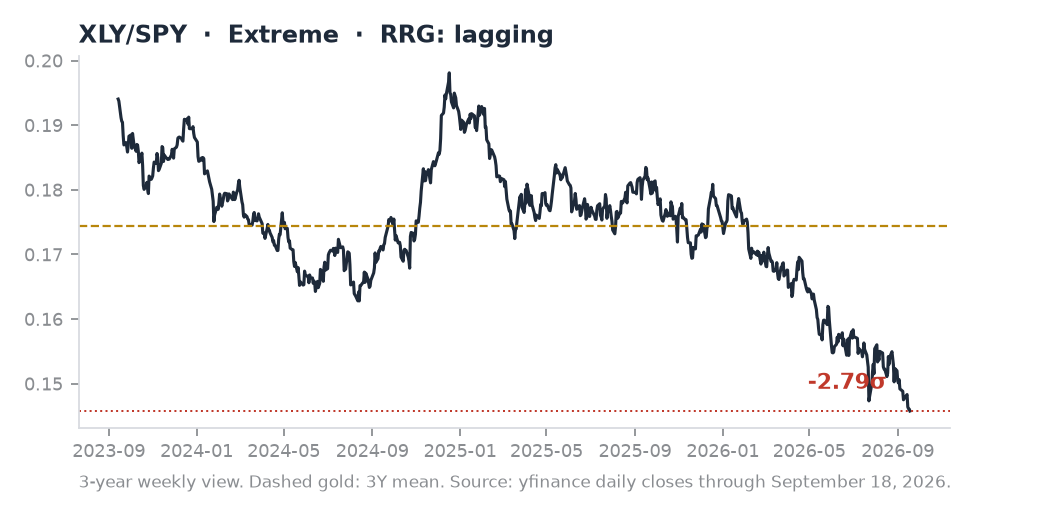
Plain-English: a extreme departure from its 3-year trend, roughly a once-per-year class move at this reading.
Returns: 1M -5.5% · 3M -7.1% · 6M -12.3% · 1Y -20.4%
Consumer discretionary cracked to -2.79 sigma with a -5.5% single month, the fastest deterioration in the table. Against staples this is the classic late-cycle consumer stress read, and it comes with the Fed explicitly hiking on an inflation print that stayed hot, core CPI +0.3% in August above the +0.2% expectation. The one-month pace is the alarm, not the level.
XLC/SPY: Signal strength -1.86σ Significant · RRG: lagging
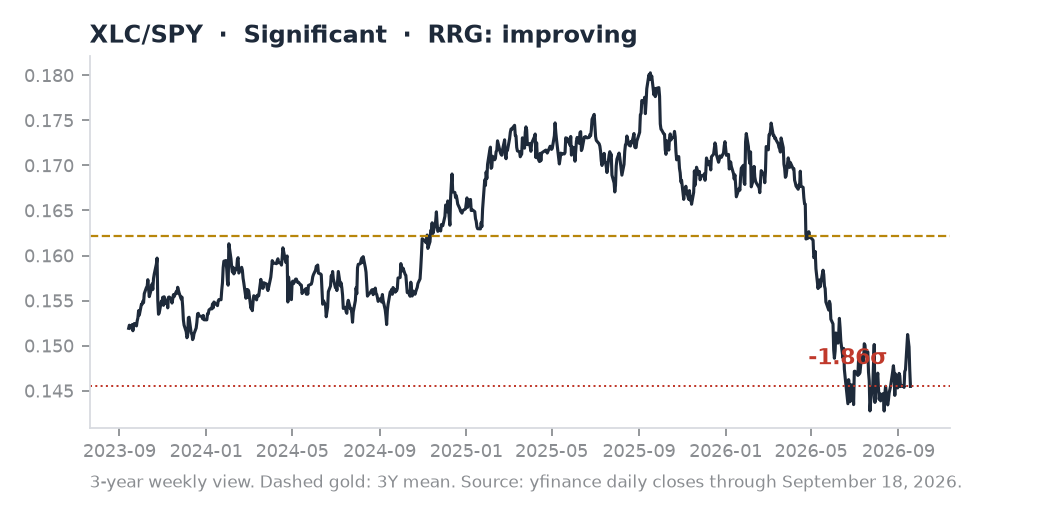
Plain-English: a significant departure from its 3-year trend, roughly meaningful at this reading.
Returns: 1M +0.5% · 3M -0.7% · 6M -15.2% · 1Y -19.3%
Communication services sat at -1.86 sigma with a flat month after -15.2% over six months. The stall is the signal here: a laggard that stops falling in a risk-on regime is either basing or being absorbed by index concentration elsewhere, and the flat 1M against a deeply negative 6M leans basing.
XLI/SPY: Signal strength -1.81σ Significant · RRG: lagging
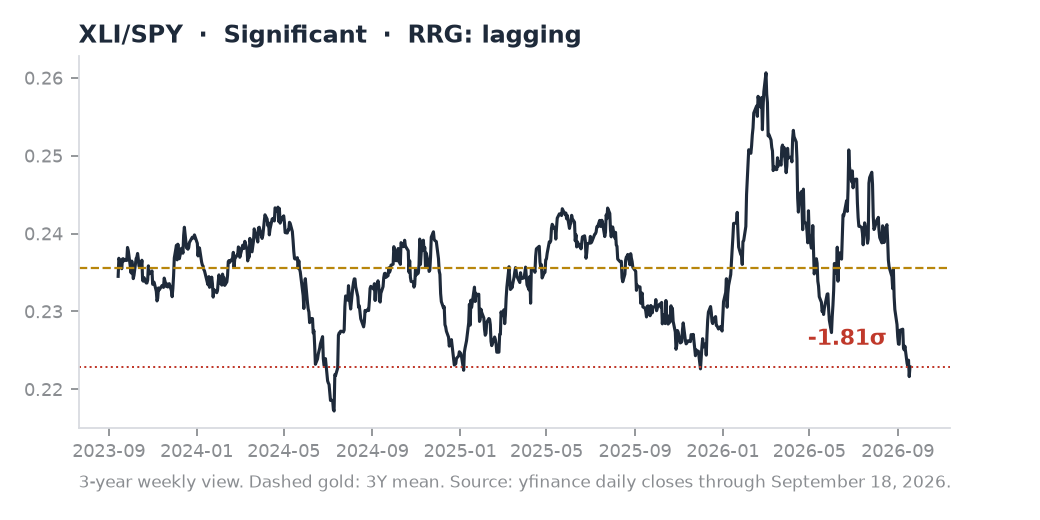
Plain-English: a significant departure from its 3-year trend, roughly meaningful at this reading.
Returns: 1M -5.8% · 3M -8.0% · 6M -10.4% · 1Y -2.8%
Industrials printed -1.81 sigma and -5.8% on the month. This is the ratio the reflation thesis leans on, and it is not cooperating: three months of -8.0% while energy leads says the market is rewarding the commodity and punishing the industrial at once, a supply-shock configuration rather than a broad reflation one.
XLRE/SPY: Signal strength -1.80σ Significant · RRG: lagging
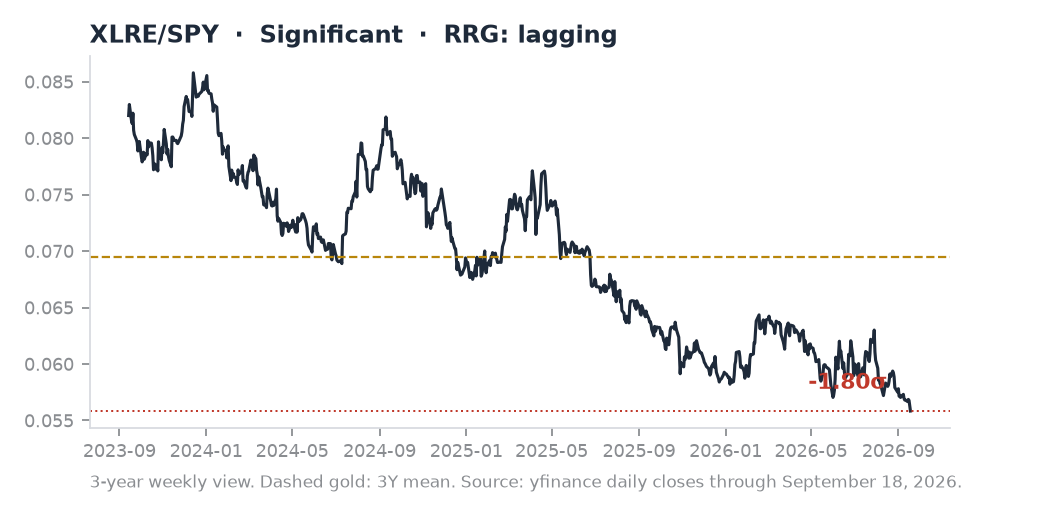
Plain-English: a significant departure from its 3-year trend, roughly meaningful at this reading.
Returns: 1M -4.6% · 3M -4.9% · 6M -12.1% · 1Y -12.4%
Real estate held -1.80 sigma, -4.6% on the month. With the funds rate at 3.75-4.00% and the statement's price-stability pledge implying more, the sector carries a directly tightening cost curve. The read is straightforward: there is no version of the present policy path that helps this ratio next quarter.
XLP/SPY: Signal strength -1.72σ Significant · RRG: lagging
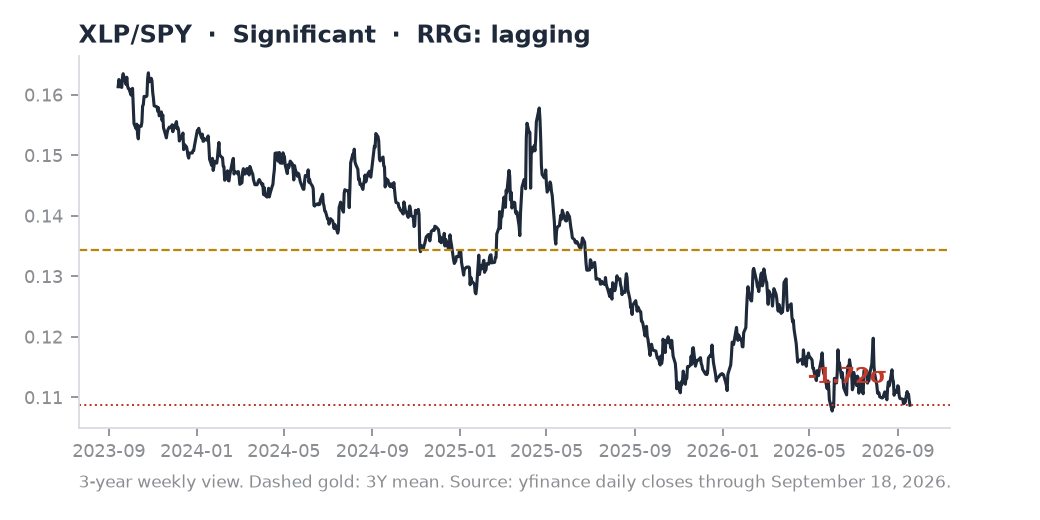
Plain-English: a significant departure from its 3-year trend, roughly meaningful at this reading.
Returns: 1M -3.4% · 3M -2.6% · 6M -12.5% · 1Y -10.7%
Staples deepened to -1.72 sigma, -3.4% on the month. The defensive complex as a group, utilities, staples, and the long bond, all sit at or beyond -1.6 sigma, which is itself the crowding datum: the market has sold everything defensive to extremes in one regime, and that is a one-way positioning setup in both directions.
TLT/SPY: Signal strength -1.64σ Significant · RRG: lagging
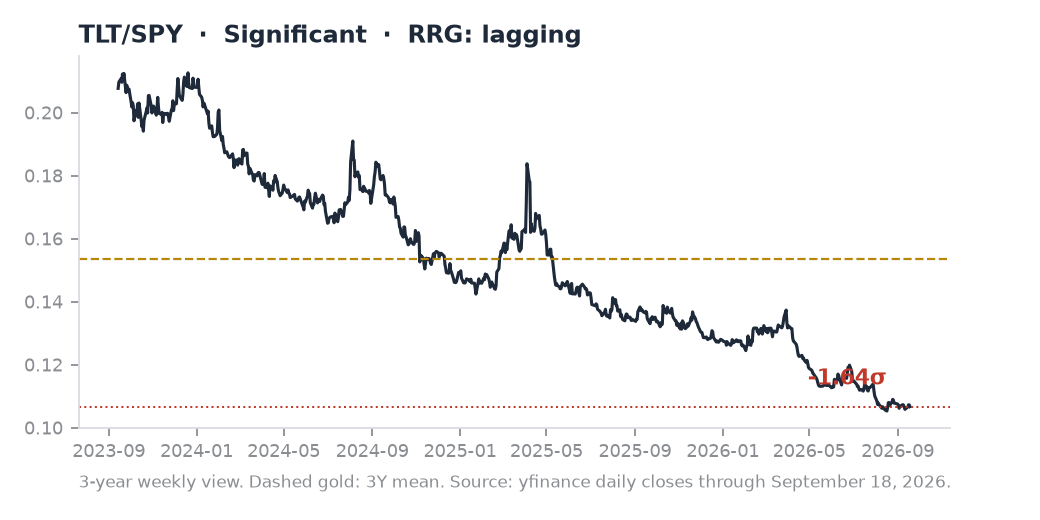
Plain-English: a significant departure from its 3-year trend, roughly meaningful at this reading.
Returns: 1M -1.2% · 3M -8.2% · 6M -19.6% · 1Y -22.0%
The long bond fell to -1.64 sigma against equities, -22.0% over the year. The repricing of duration under a Fed that has now hiked into strength three times is the widest single-year gap in the table. It is also the asymmetry warning for the equity read: the same inflation that justifies the hikes is the one variable that turns this week's confirmation into next quarter's disconfirmation.
SDY/SPY: Signal strength -1.63σ Significant · RRG: lagging
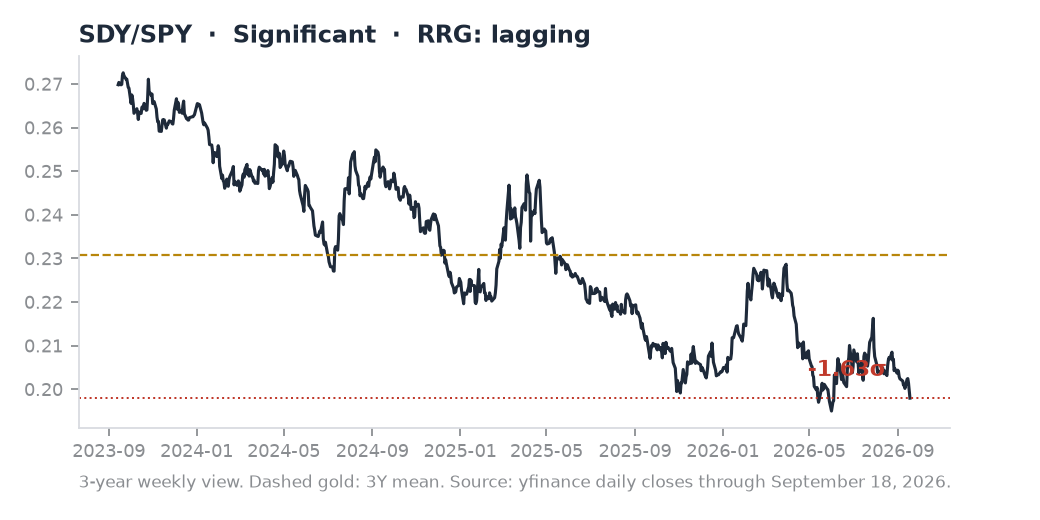
Plain-English: a significant departure from its 3-year trend, roughly meaningful at this reading.
Returns: 1M -4.2% · 3M -1.8% · 6M -10.5% · 1Y -6.7%
Dividend aristocrats printed -1.63 sigma, -10.5% over six months. The yield-factor complex losing to the index while credit confirms is the yield-curve steepening trade showing up in equity factor form, the same signal TLT/SPY carries, expressed one step down the risk curve.
XLB/SPY: Signal strength -1.42σ Notable · RRG: lagging
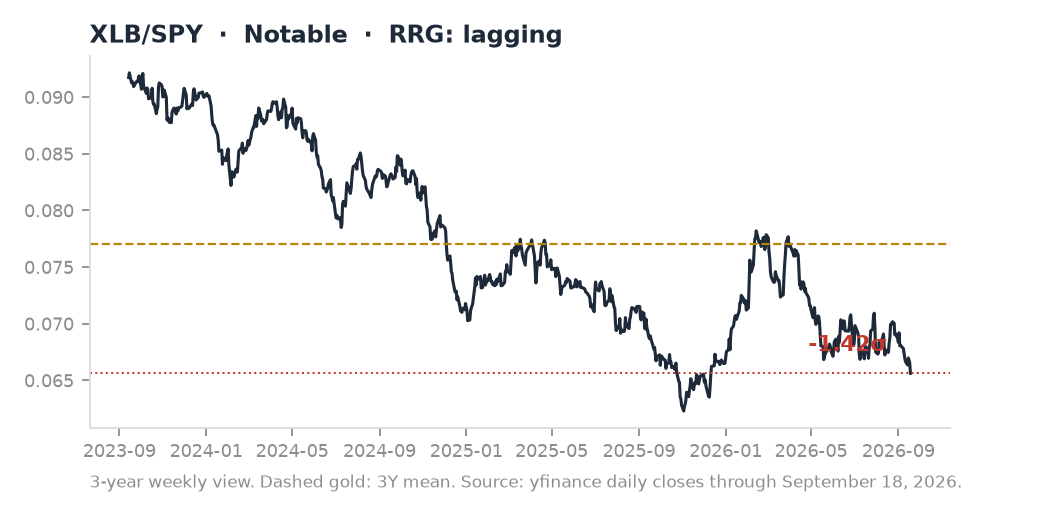
Plain-English: a notable departure from its 3-year trend, roughly clearly above or below trend at this reading.
Returns: 1M -3.9% · 3M -5.4% · 6M -9.3% · 1Y -4.8%
Materials printed -1.42 sigma and -3.9% on the month, the quiet member of the cyclical complex. Paired with industrials at -1.81 sigma, the entire capex-sensitive group is losing to the index while energy leads, which confirms the supply-shock read over the demand-reflation one. The sector's -9.3% six-month path has no basing signal in it yet.
XLF/SPY: Signal strength -1.44σ Notable · RRG: lagging
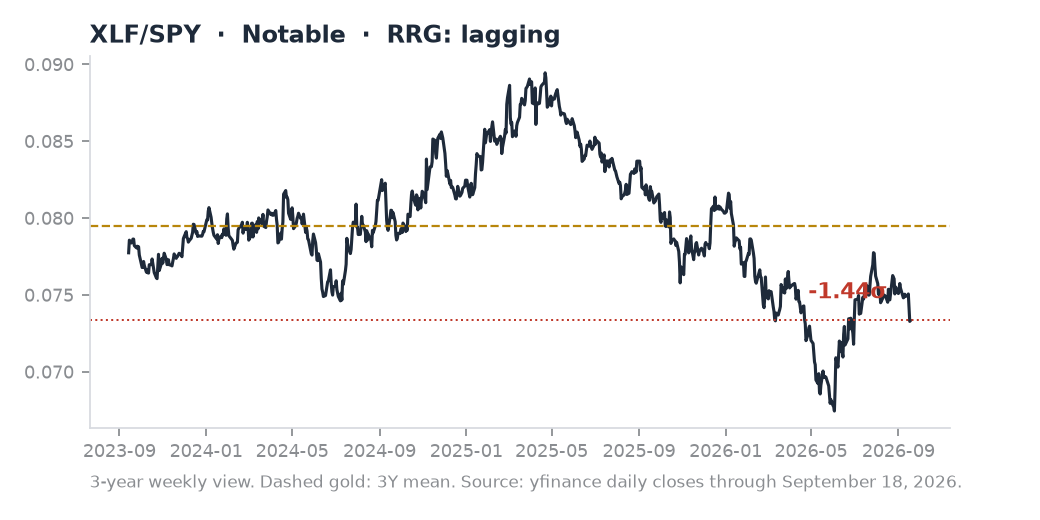
Plain-English: clearly below its 3-year trend, but not at a signal level.
Returns: 1M -1.9% · 3M +2.2% · 6M -1.2% · 1Y -10.6%
Financials sit at -1.44 sigma, -1.9% on the month. The anomaly in the reading is the year, -10.6% against a Fed actively hiking, the configuration banks are supposed to love. The flat three-month against EUFN/SPY's leadership says the market is charging US banks a premium for the same rate path it rewards European banks for, and the gap is the regulatory and credit-cycle question, not the rates one.
Lumber/Gold: Signal strength -1.36σ Notable · RRG: lagging
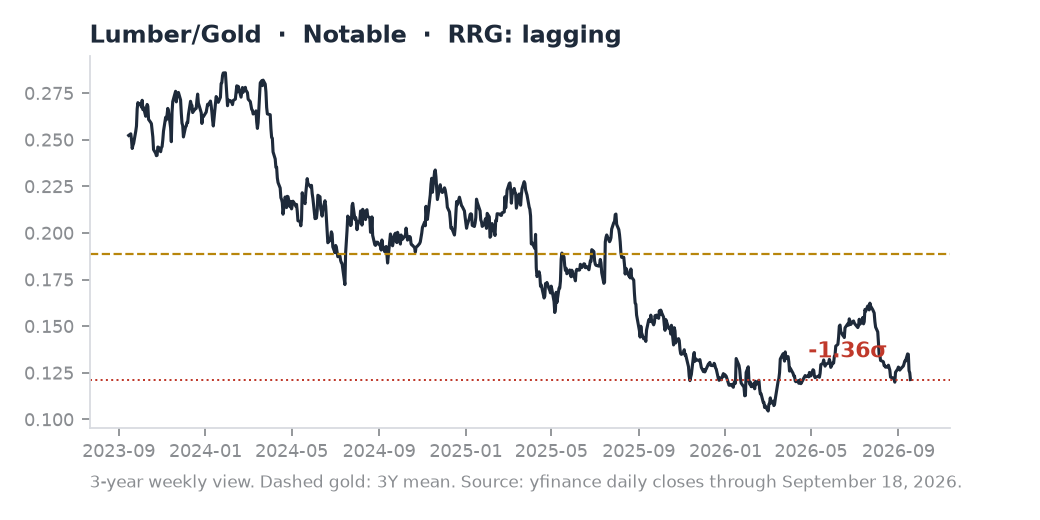
Plain-English: clearly below trend. The extreme from the last edition has partially normalized without the direction changing.
Returns: 1M -5.1% · 3M -18.6% · 6M -8.3% · 1Y -20.4%
Lumber/Gold holds -1.36 sigma, -5.1% on the month, -18.6% over three. Run #29 flagged the -2.16 sigma extreme as the death of the reflation trade; the partial normalization since is mean reversion, not recovery, and the series is still deteriorating at a 5% monthly pace. The real-economy signal stands.
What Would Change My View
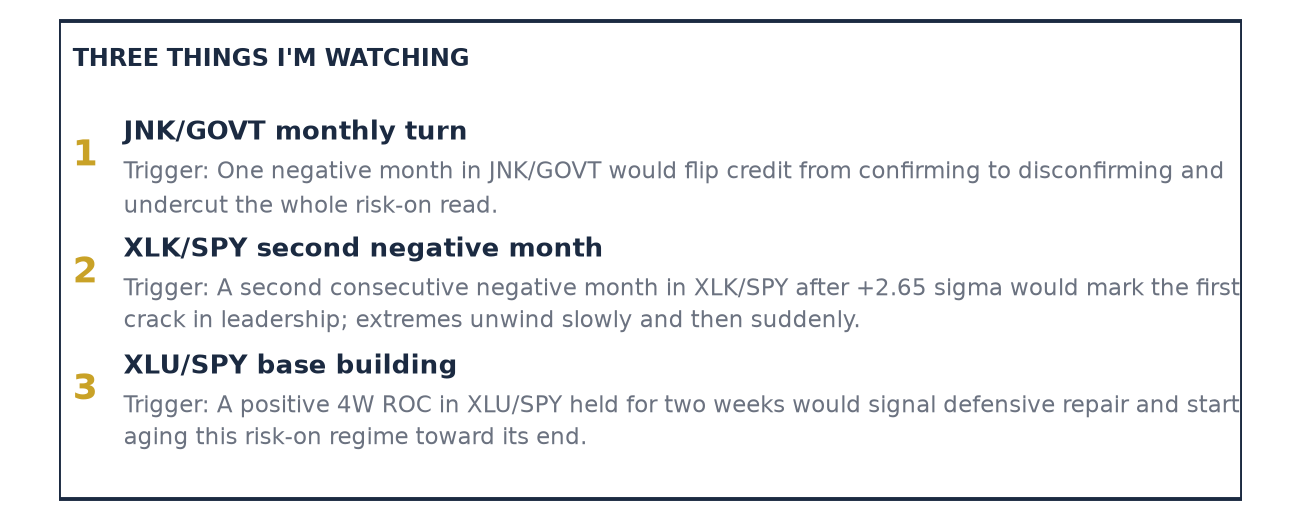
- XLU/SPY posting a positive 4W ROC held for two consecutive weeks. Defensive repair is the regime's endgame signal, and it ages the risk-on read toward rotation.
- JNK/GOVT printing a negative month. Credit is the confirmation under everything above; one clean negative month withdraws it.
- XLK/SPY turning negative over three months. A +2.65 sigma extreme that fails on momentum rather than time is the 2000 configuration, and it would flip the concentration warning from footnote to headline.
- Lumber/Gold rising more than 5% in a month. The real-economy softness signal reversing with force would rehabilitate the reflation thesis this column has been bearish on since Run #29.
The Week in Context
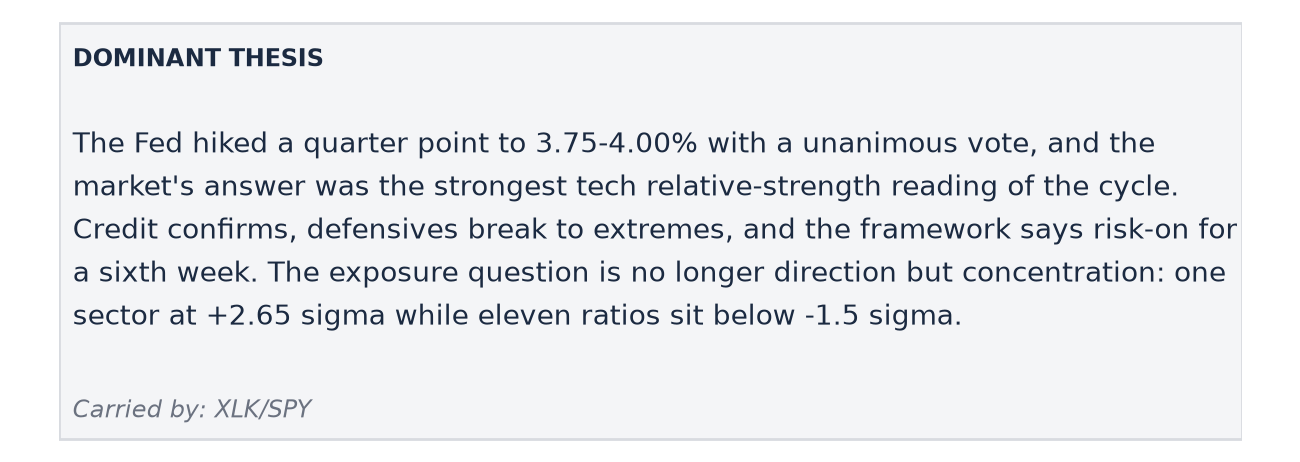
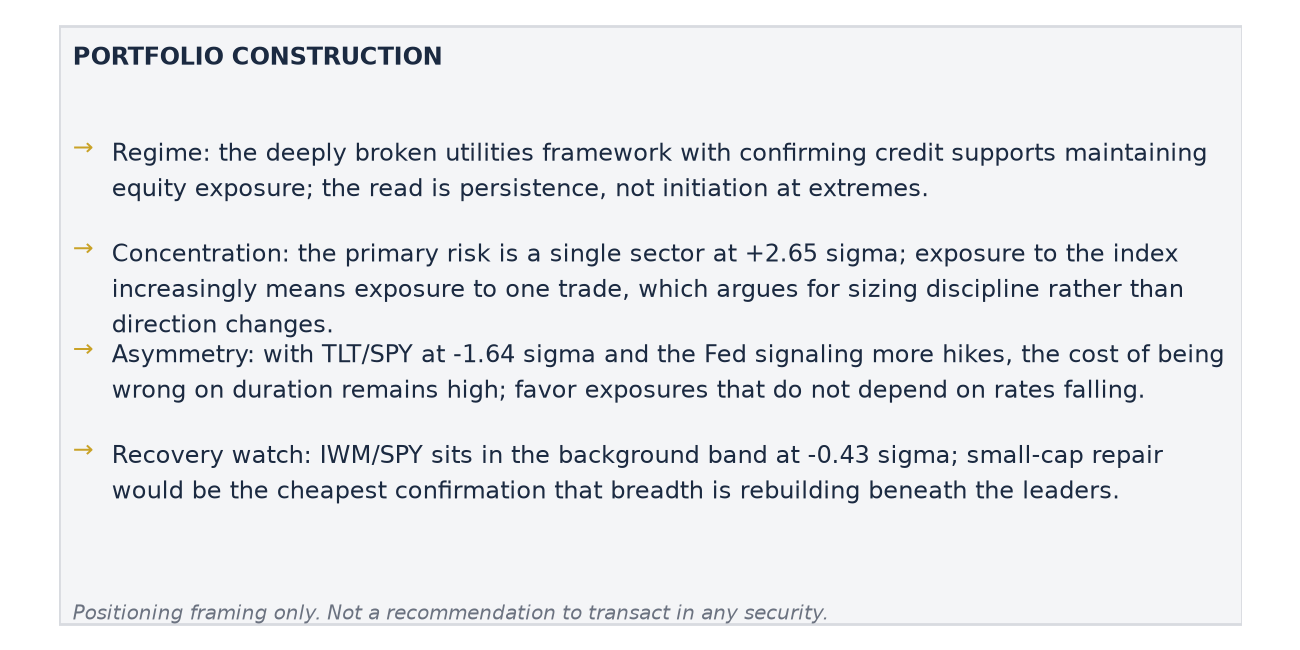
The week's calendar was the thesis. August CPI on September 11 printed +0.4% headline and +0.3% core against a +0.2% core expectation, keeping pressure on the Fed to act, per Reuters. The FOMC hiked 25 basis points on September 16 to a 3.75-4.00% target range, a unanimous 12-0 vote, with the statement citing elevated inflation, a solid expansion, strong productivity growth, and robust capital investment, per federalreserve.gov. The Bank of Japan followed with its own hike to 1.25%, a 31-year high, on a 7-2 vote, per the BOJ announcement. The S&P 500 closed at 7,637.76 on September 17 per FRED, and SPY finished the week at 761.69 on Friday, September 18, per yfinance. The market's answer to a tightening Fed, a tightening BOJ, and a hot inflation print was the strongest tech leadership reading of the cycle. That is either the most confident market of the hiking era or the most concentrated one, and the honest answer is that the data in this edition does not yet distinguish between them. The first thing to watch next week is the JNK/GOVT monthly print; everything else in this edition is downstream of it.
Forward Calls: Testable Predictions for Run #31
- [XLU/SPY] The 4W ROC remains negative at the next edition's close. Reasoning: sixth-week framework streaks with -5.7% monthly pace do not repair in two weeks.
- [XLK/SPY] The 1M return stays positive at the next edition's close. Reasoning: extreme leadership with confirming credit decays slowly; the 2000-style break requires momentum failure first.
- [JNK/GOVT] Z stays above +1.0 sigma at the next edition's close. Reasoning: credit has absorbed three Fed hikes without a negative month.
- [Lumber/Gold] The 1M return is negative at the next edition's close. Reasoning: -1.36 sigma and still falling at 5% monthly pace; no reversal signal present.
- [XLY/SPY] Z ends below -2.0 sigma at the next edition's close. Reasoning: -2.79 sigma with the consumer directly in the Fed's tightening path.
- [TLT/SPY] The 1M return is negative at the next edition's close. Reasoning: price-stability language at 3.75-4.00% keeps repricing duration against equities.
All ratio, return, and Z-score readings computed from daily closes through Friday, September 18, 2026 (yfinance). Macro facts sourced inline: FOMC statement September 16, 2026 (federalreserve.gov); August CPI (Reuters, September 11, 2026); Bank of Japan decision (boj.or.jp, September 18, 2026); S&P 500 level (FRED, September 17, 2026).
The Lead-Lag Report is provided by Lead-Lag Publishing, LLC. All opinions and views mentioned in this report constitute our judgments as of the date of writing and are subject to change at any time. Information within this material is not intended to be used as a primary basis for investment decisions and should also not be construed as advice meeting the particular investment needs of any individual investor. Trading signals produced by the Lead-Lag Report are independent of other services provided by Lead-Lag Publishing, LLC or its affiliates, and positioning of accounts under their management may differ. Please remember that investing involves risk, including loss of principal, and past performance may not be indicative of future results. Lead-Lag Publishing, LLC, its members, officers, directors and employees expressly disclaim all liability in respect to actions taken based on any or all of the information on this writing.Background Band: The Readings Beneath the Signal
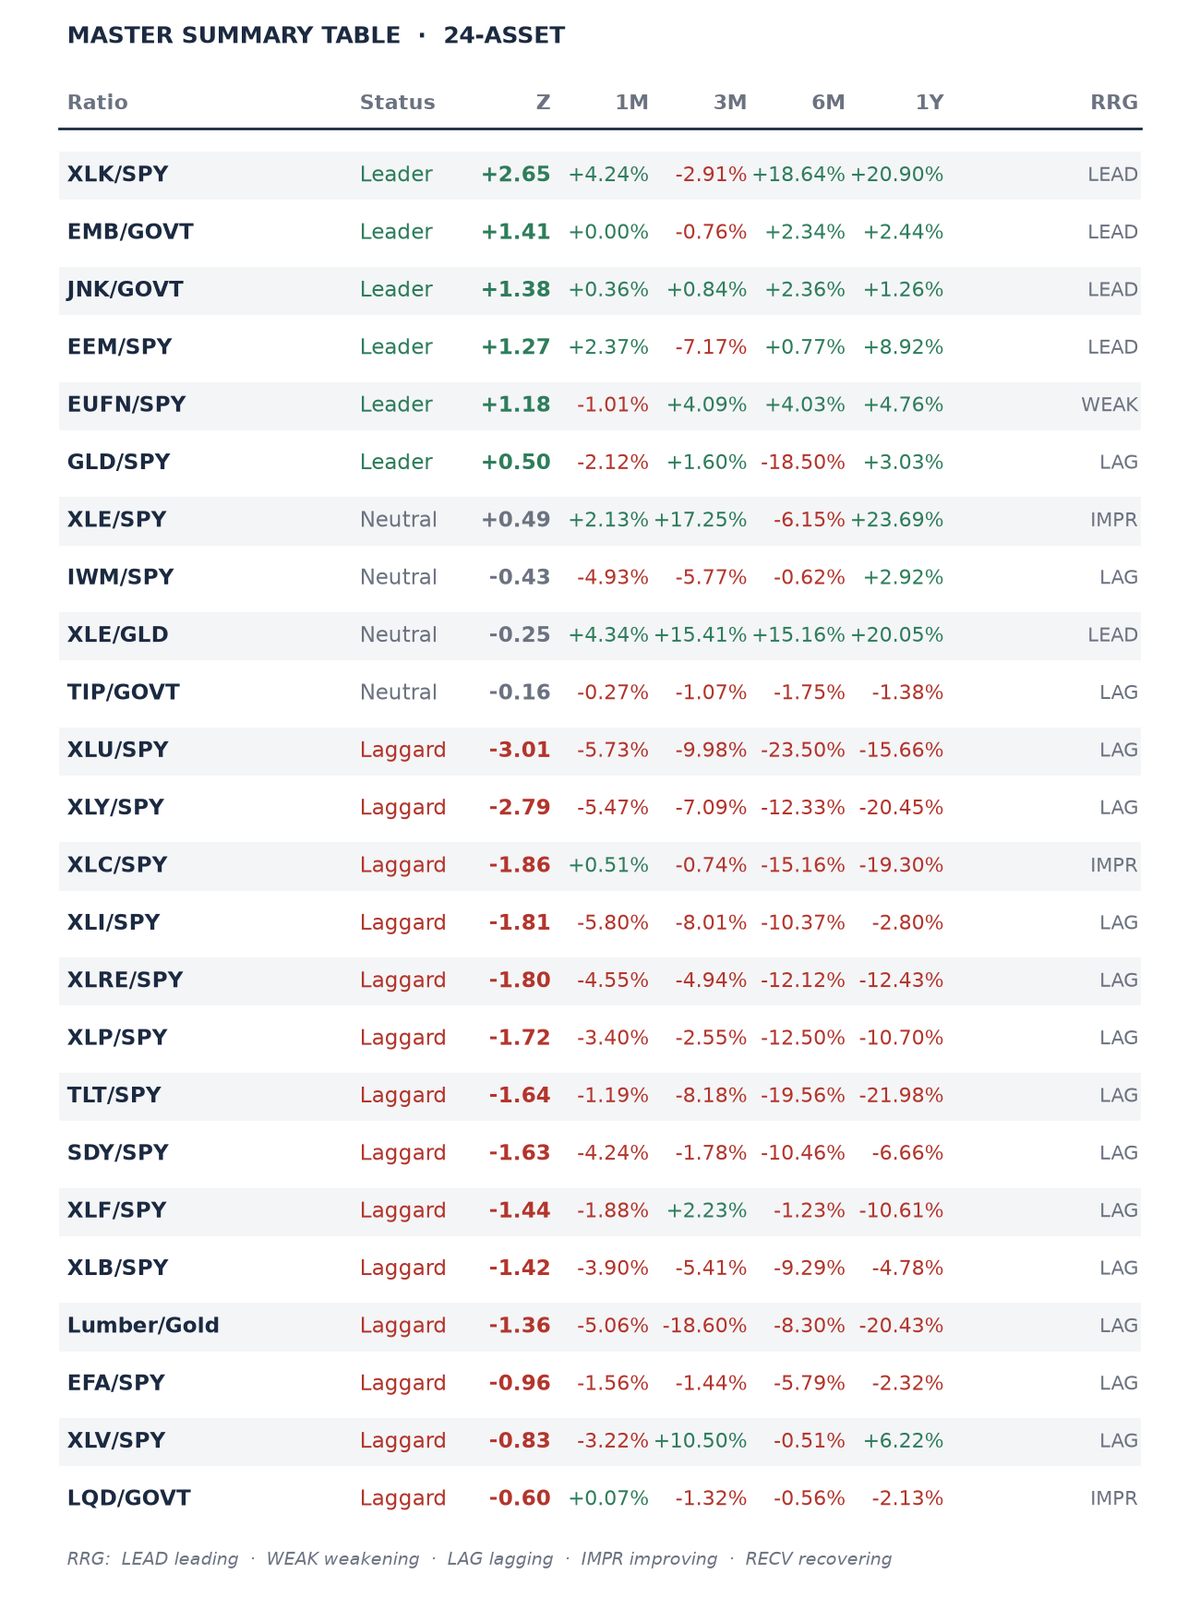
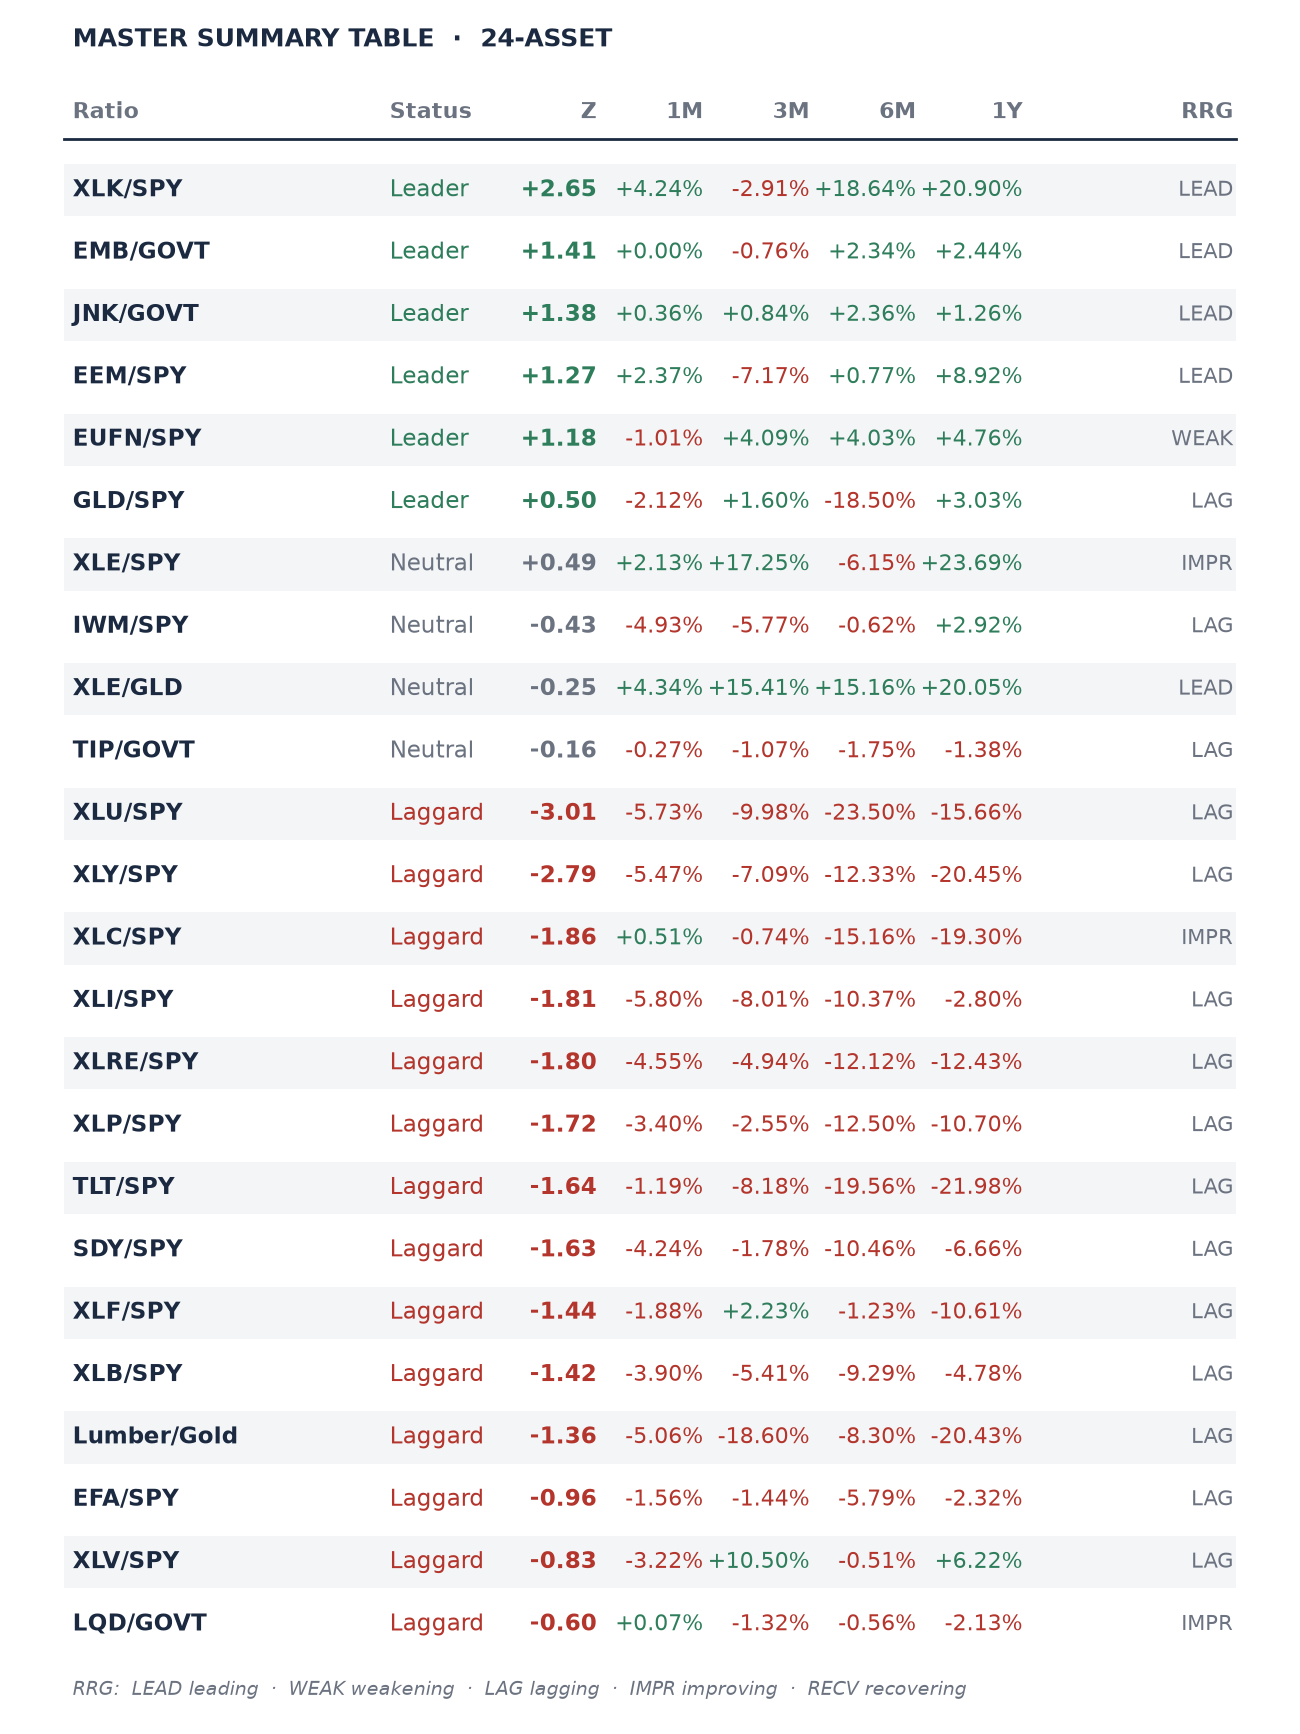
Six ratios sit below the Notable threshold this week. They carry no signal on their own, but they complete the 24-ratio picture, and each chart is included so every reading in the master table is visible in full.
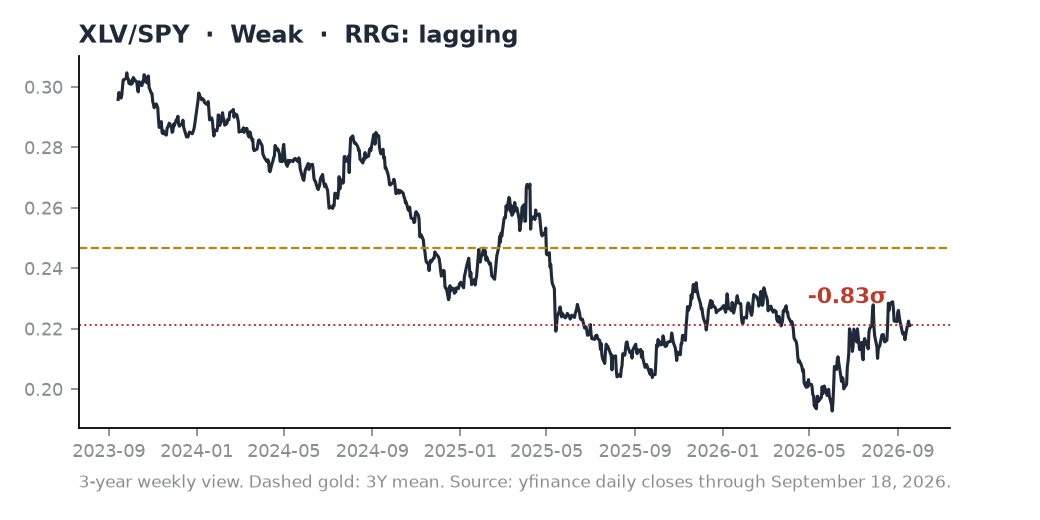
XLV/SPY at -0.83 sigma: healthcare quietly losing to the index, -3.2% on the month, a laggard in trend but not yet at a signal level.
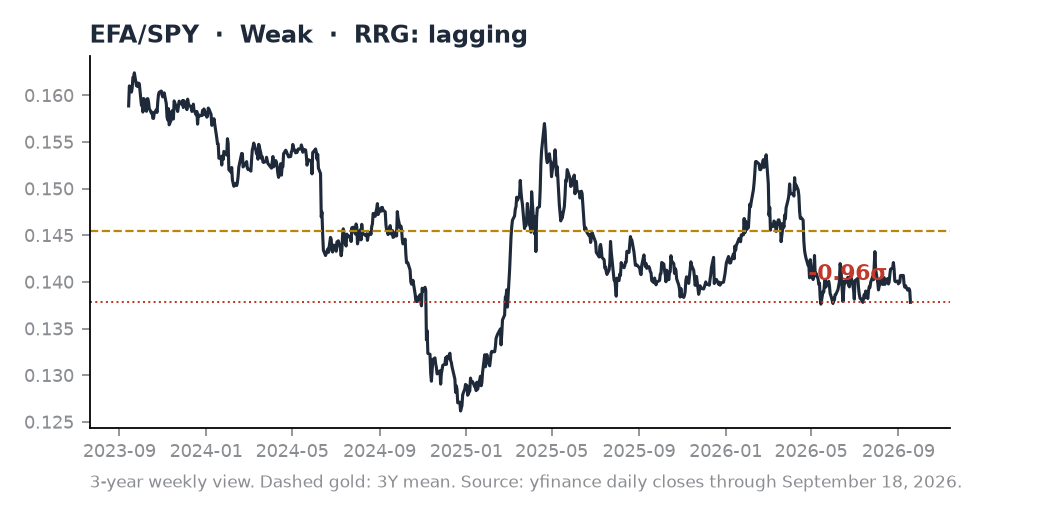
EFA/SPY at -0.96 sigma: developed international ex-US remains the missing allocation, -1.6% on the month against a domestic index at cycle highs.
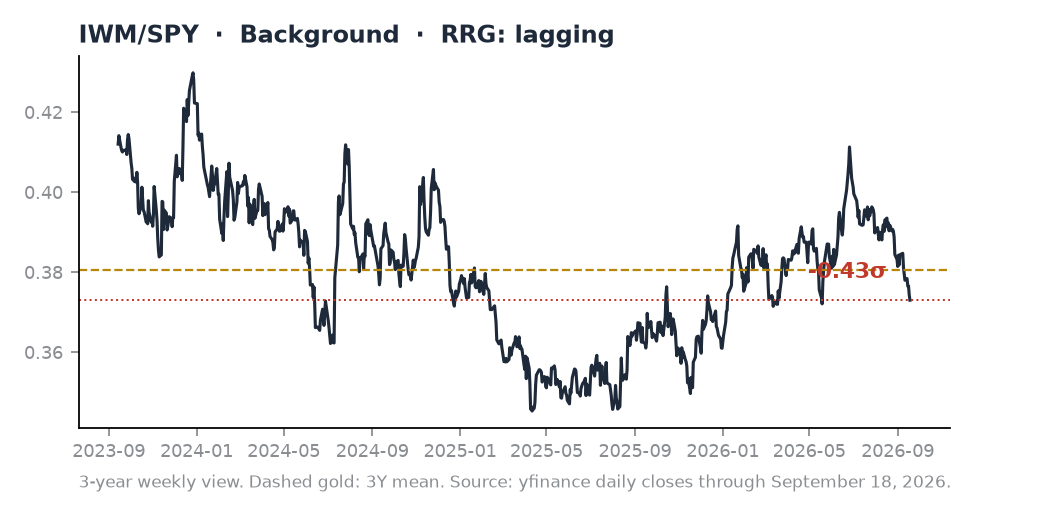
IWM/SPY at -0.43 sigma: small caps in the background band at -4.9% on the month, the ratio whose repair would be the cheapest breadth confirmation available.
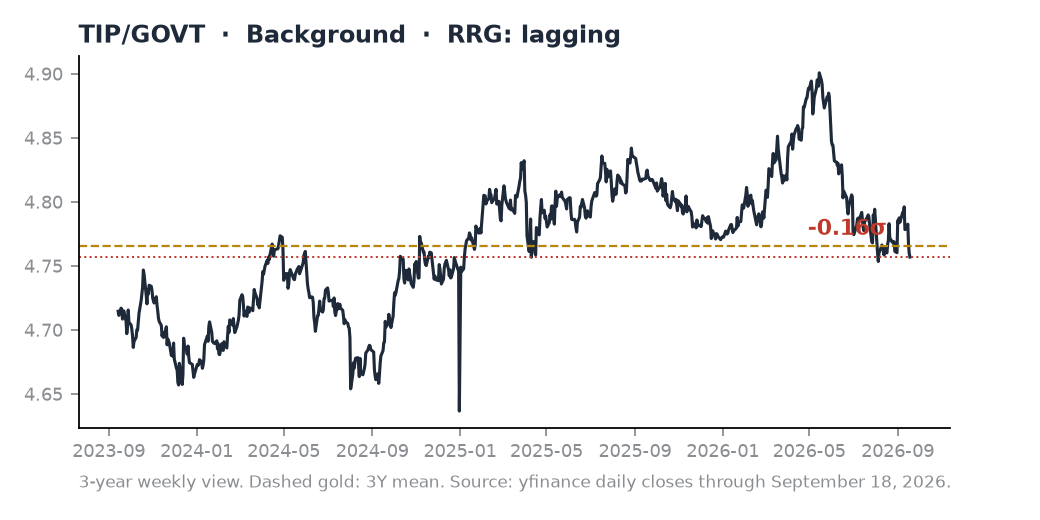
TIP/GOVT at -0.16 sigma: breakevens flat against nominals; the inflation fight the Fed says it is still waging shows no new direction in this ratio.
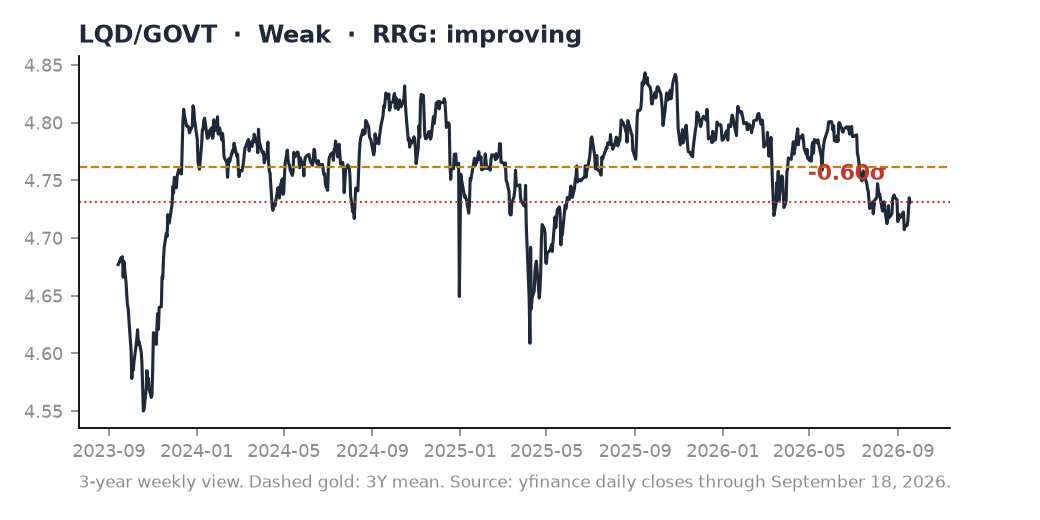
LQD/GOVT at -0.60 sigma: investment-grade credit flat on the month, and the improving quadrant shift is the only directional change in this group.
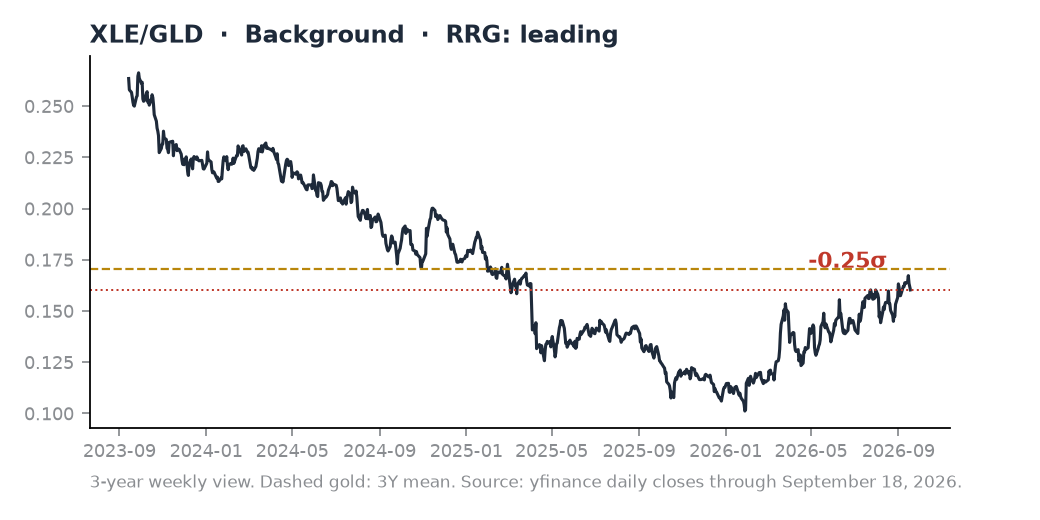
XLE/GLD at -0.25 sigma: energy versus gold at +4.3% on the month and +15.2% over six, the reflation-versus-hard-money pairing still resolving toward the commodity trade.
>