The Credit Signal: Utilities Just Flipped the JOJO.Index to Credit-Off
Weekly read on the JOJO.Index credit signal: it moved to credit-off as high yield spreads rose 80 bps from their 12-month low.
Today’s Lead-Lag Report post is sponsored by Infrastructure Capital Advisors

Jay Hatfield on markets and the economy, today at 2:00 PM ET
Infrastructure Capital Advisors sponsors this Lead-Lag Live webinar. Founder and CEO Jay Hatfield joins Michael Gayed today, October 26, at 2:00 PM ET for a live look at markets and the economy, built for advisors who field these questions from clients every week. Jay will explain what he is watching and why, in plain English, and take questions live.
On the agenda:
- Housing starts, mortgage rates and what the Fed may do next
- How a real-time inflation measure compares with reported CPI
- Where credit markets stand on AI infrastructure financing
- How the 10-year yield relates to Fed policy
Registration is free and takes under a minute. Bring the questions your clients have been asking you about rates, housing, inflation and credit. Register free here.
DISCLAIMER – PLEASE READ: Sponsored by Infrastructure Capital Advisors, LLC. Views expressed are those of the speaker and are not investment advice. This is sponsored advertising content for which Lead-Lag Publishing, LLC has been paid a fee. The information provided in the link is solely the creation of Infrastructure Capital Advisors, LLC. Lead-Lag Publishing, LLC does not guarantee the accuracy or completeness of the information provided in the link or make any representation as to its quality, and expressly disclaims any responsibility for action taken in connection with the information provided in the link.
The Credit Signal is a weekly read on one question: is the equity market telling credit to get defensive? Data through Friday, 10/23/2026.
The signal this week: credit-off
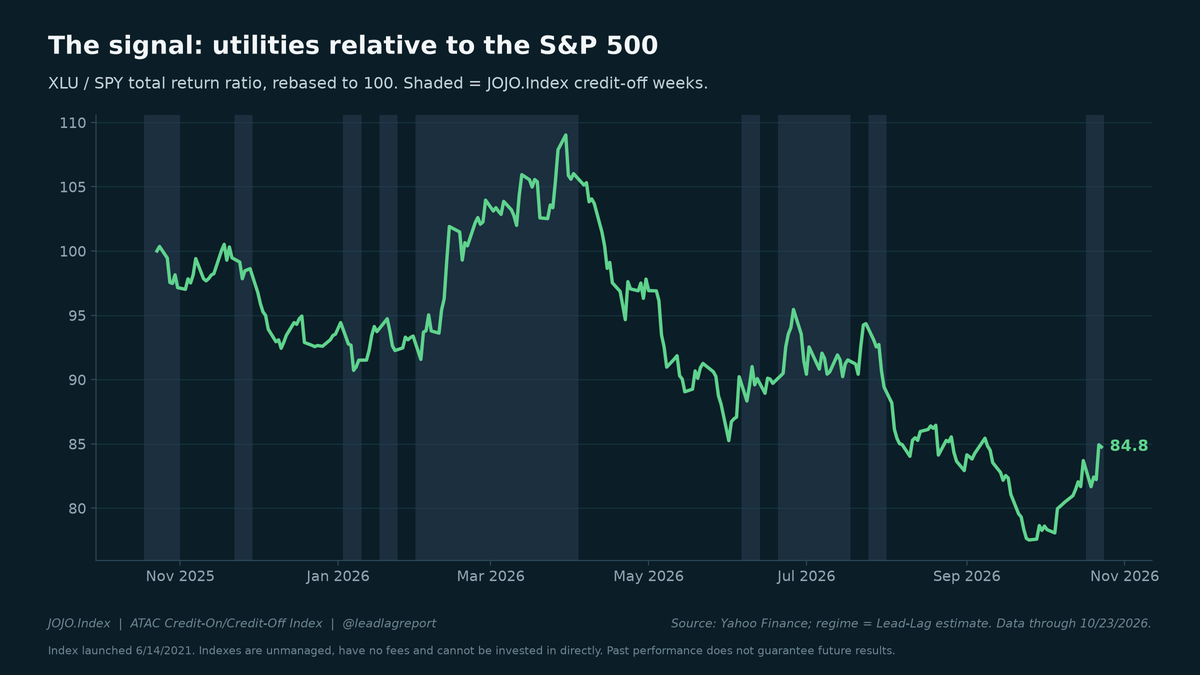
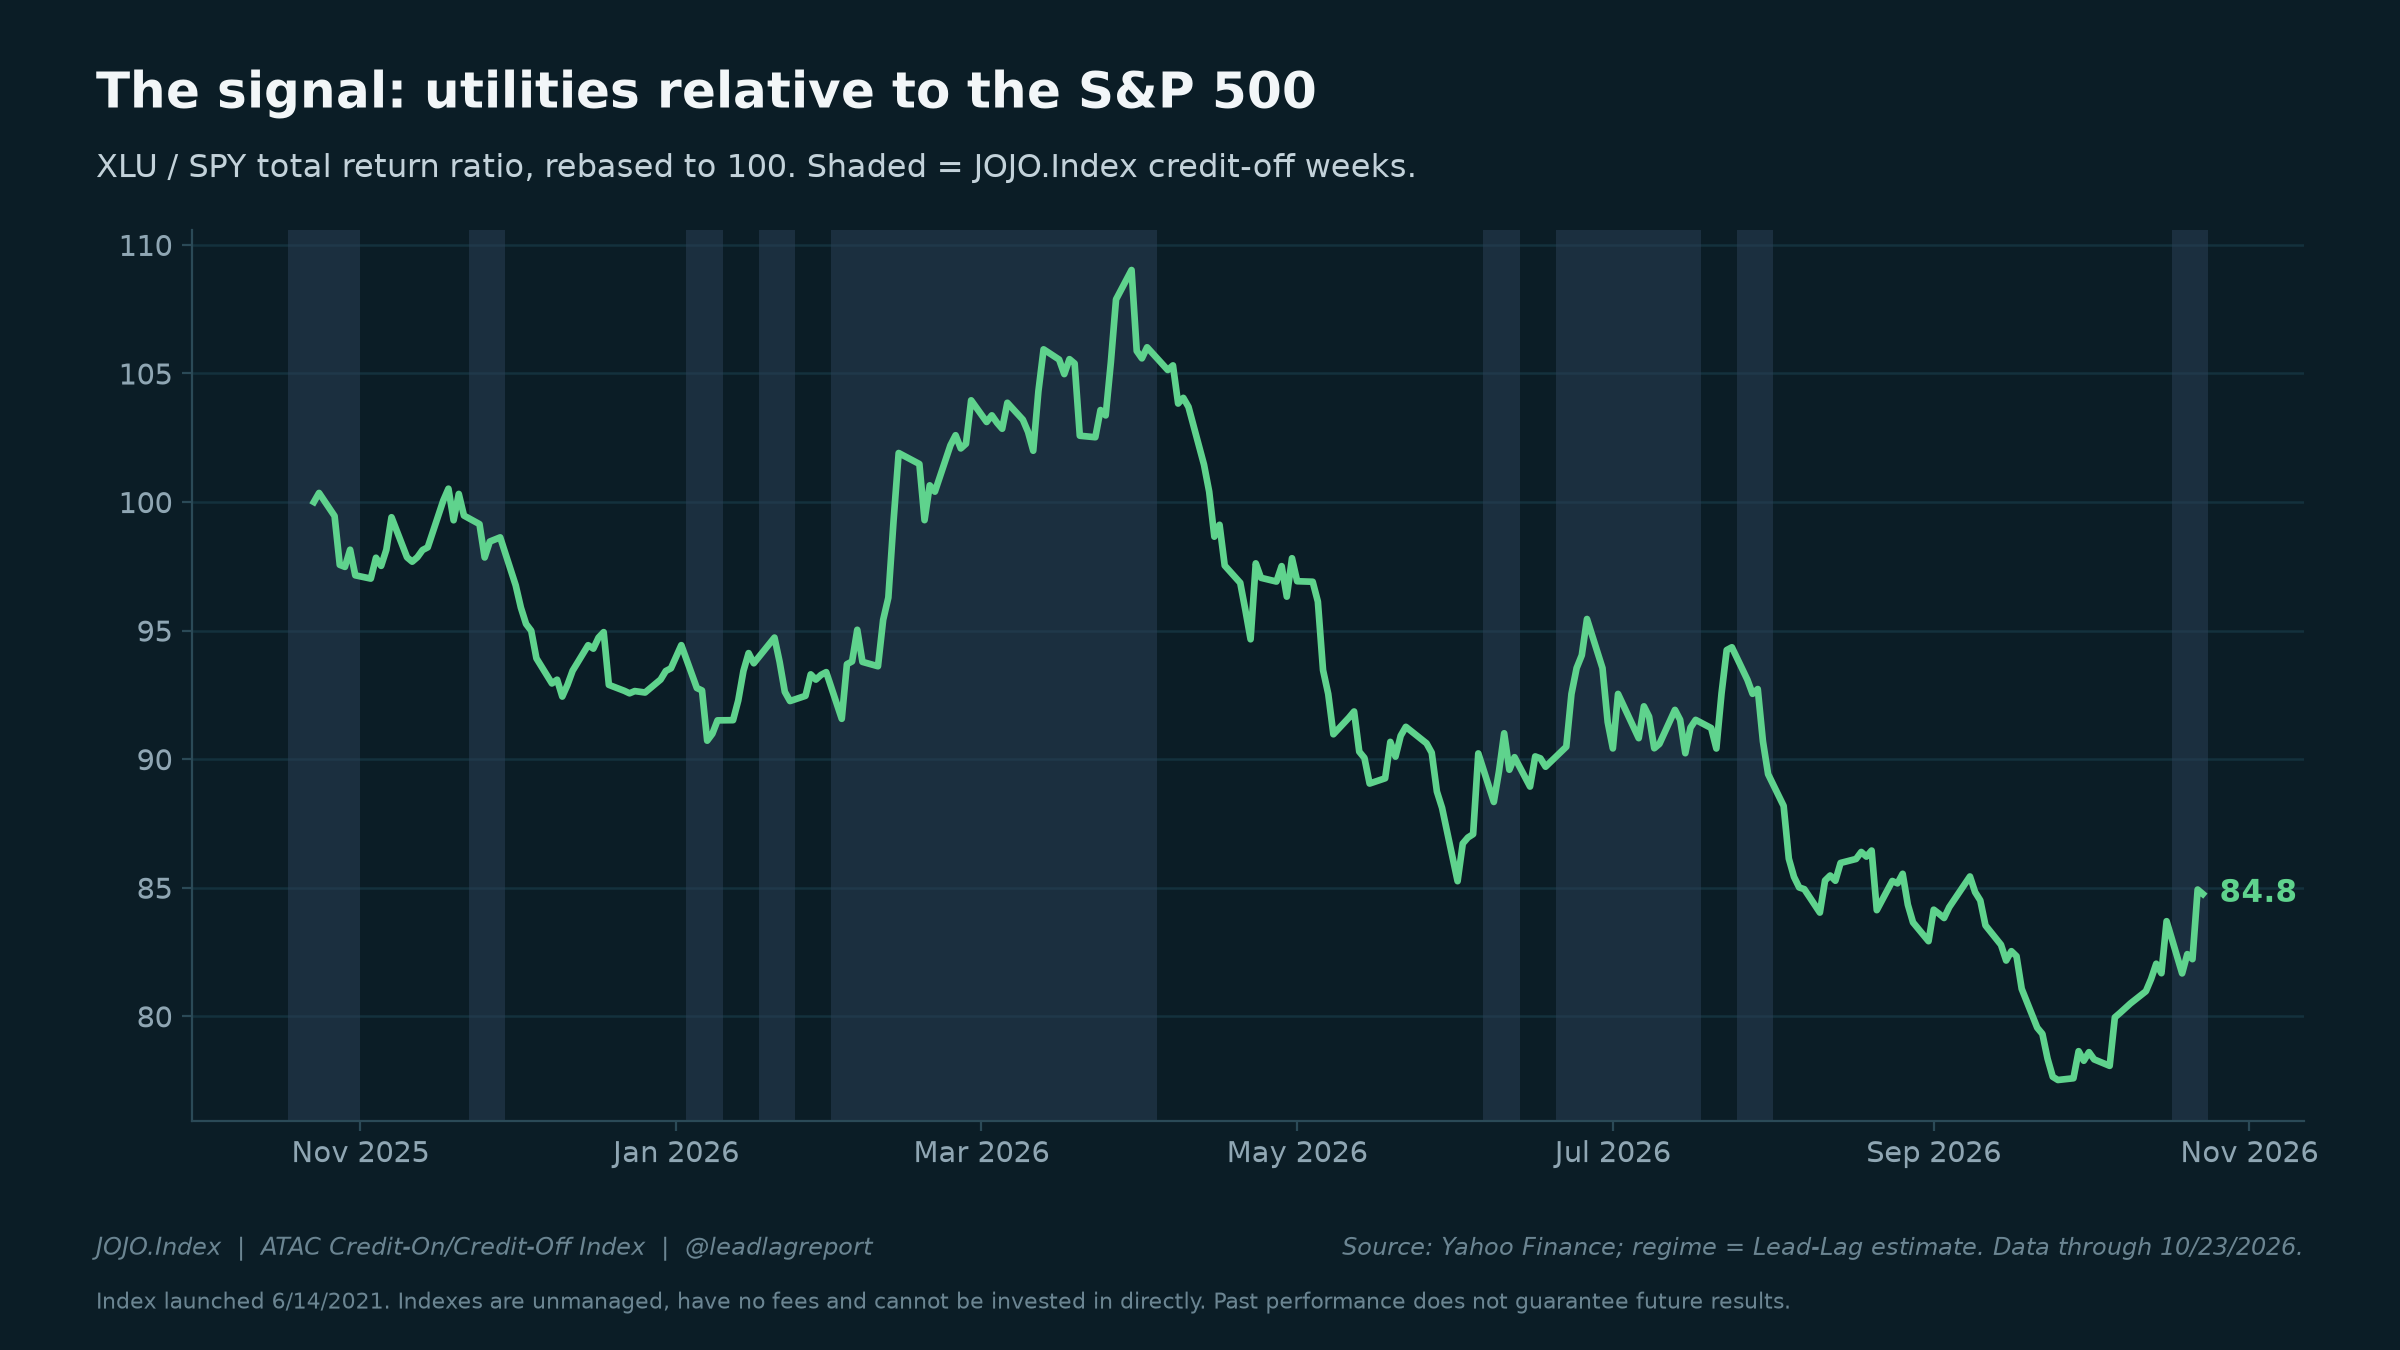
The JOJO.Index asks one thing every week. Are utilities leading the S&P 500? If yes, it sits in long Treasuries. If no, it holds high yield.
Last week the answer changed. The index moved to credit-off, long Treasuries, for the first time since late July. Utilities are up 9.33% against the S&P 500 over the past four weeks.
What credit spreads are doing
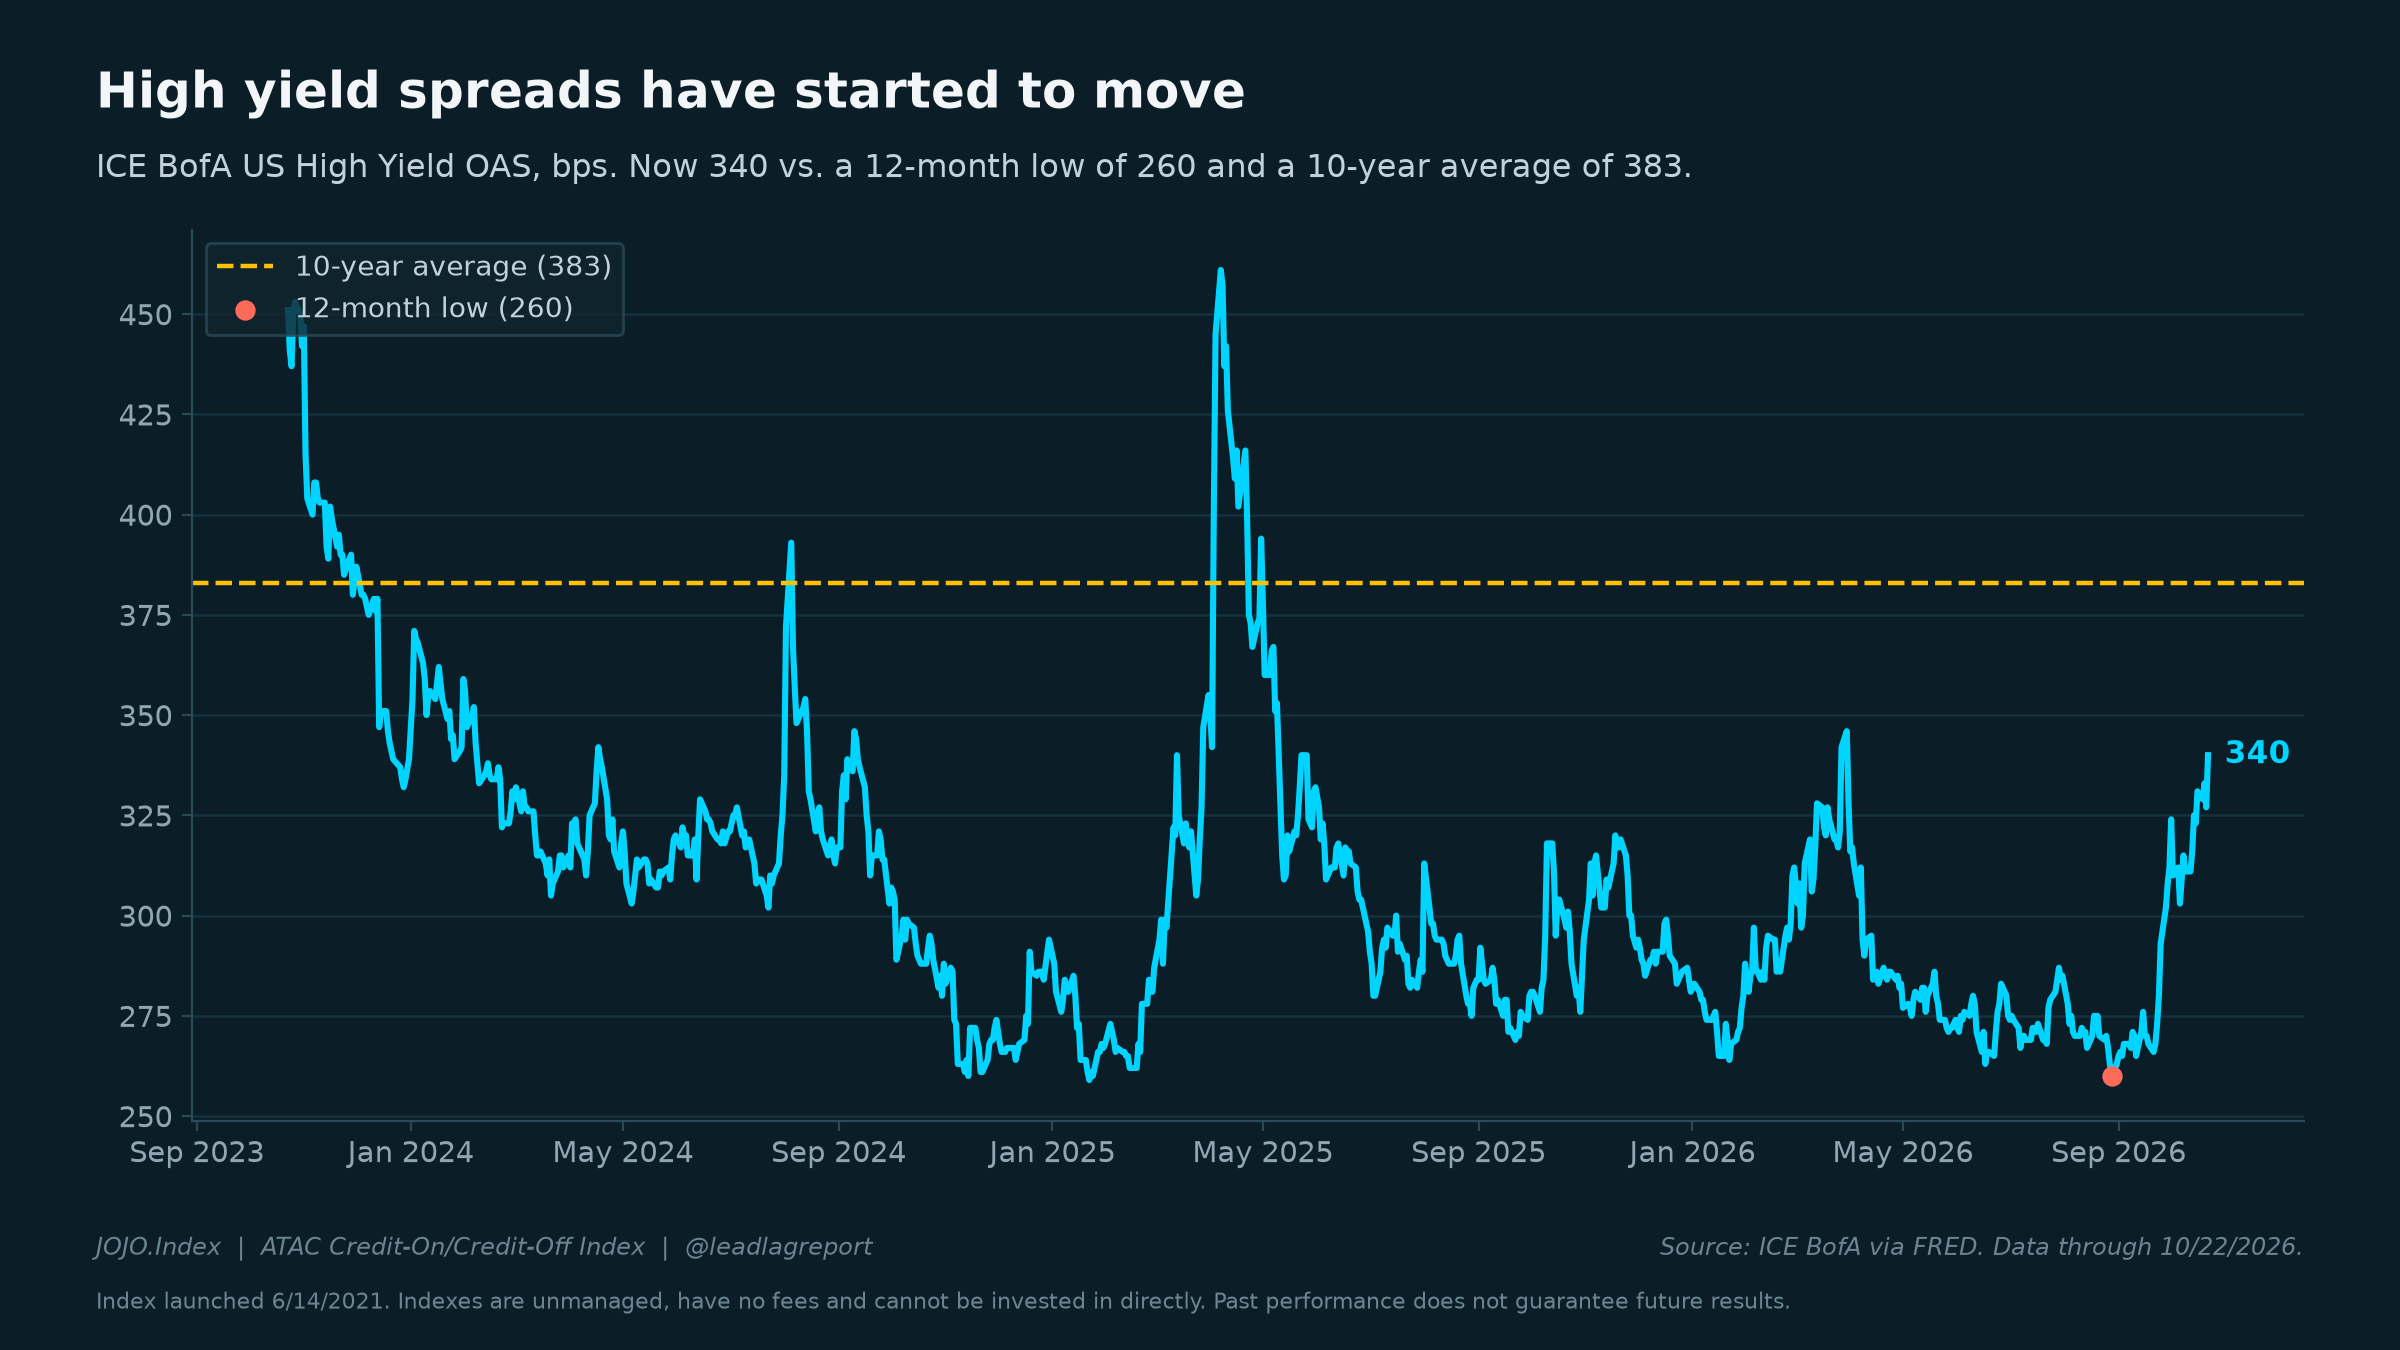
High yield spreads hit 260 bps on Aug 28, a 12-month low. They were 340 bps on 10/22, up 80 bps in eight weeks. That is still below the 10-year average of 383, and still in the bottom quarter of readings since 1997. Spreads have started to move. They have not repriced.
From the backtest: the 2011 downgrade
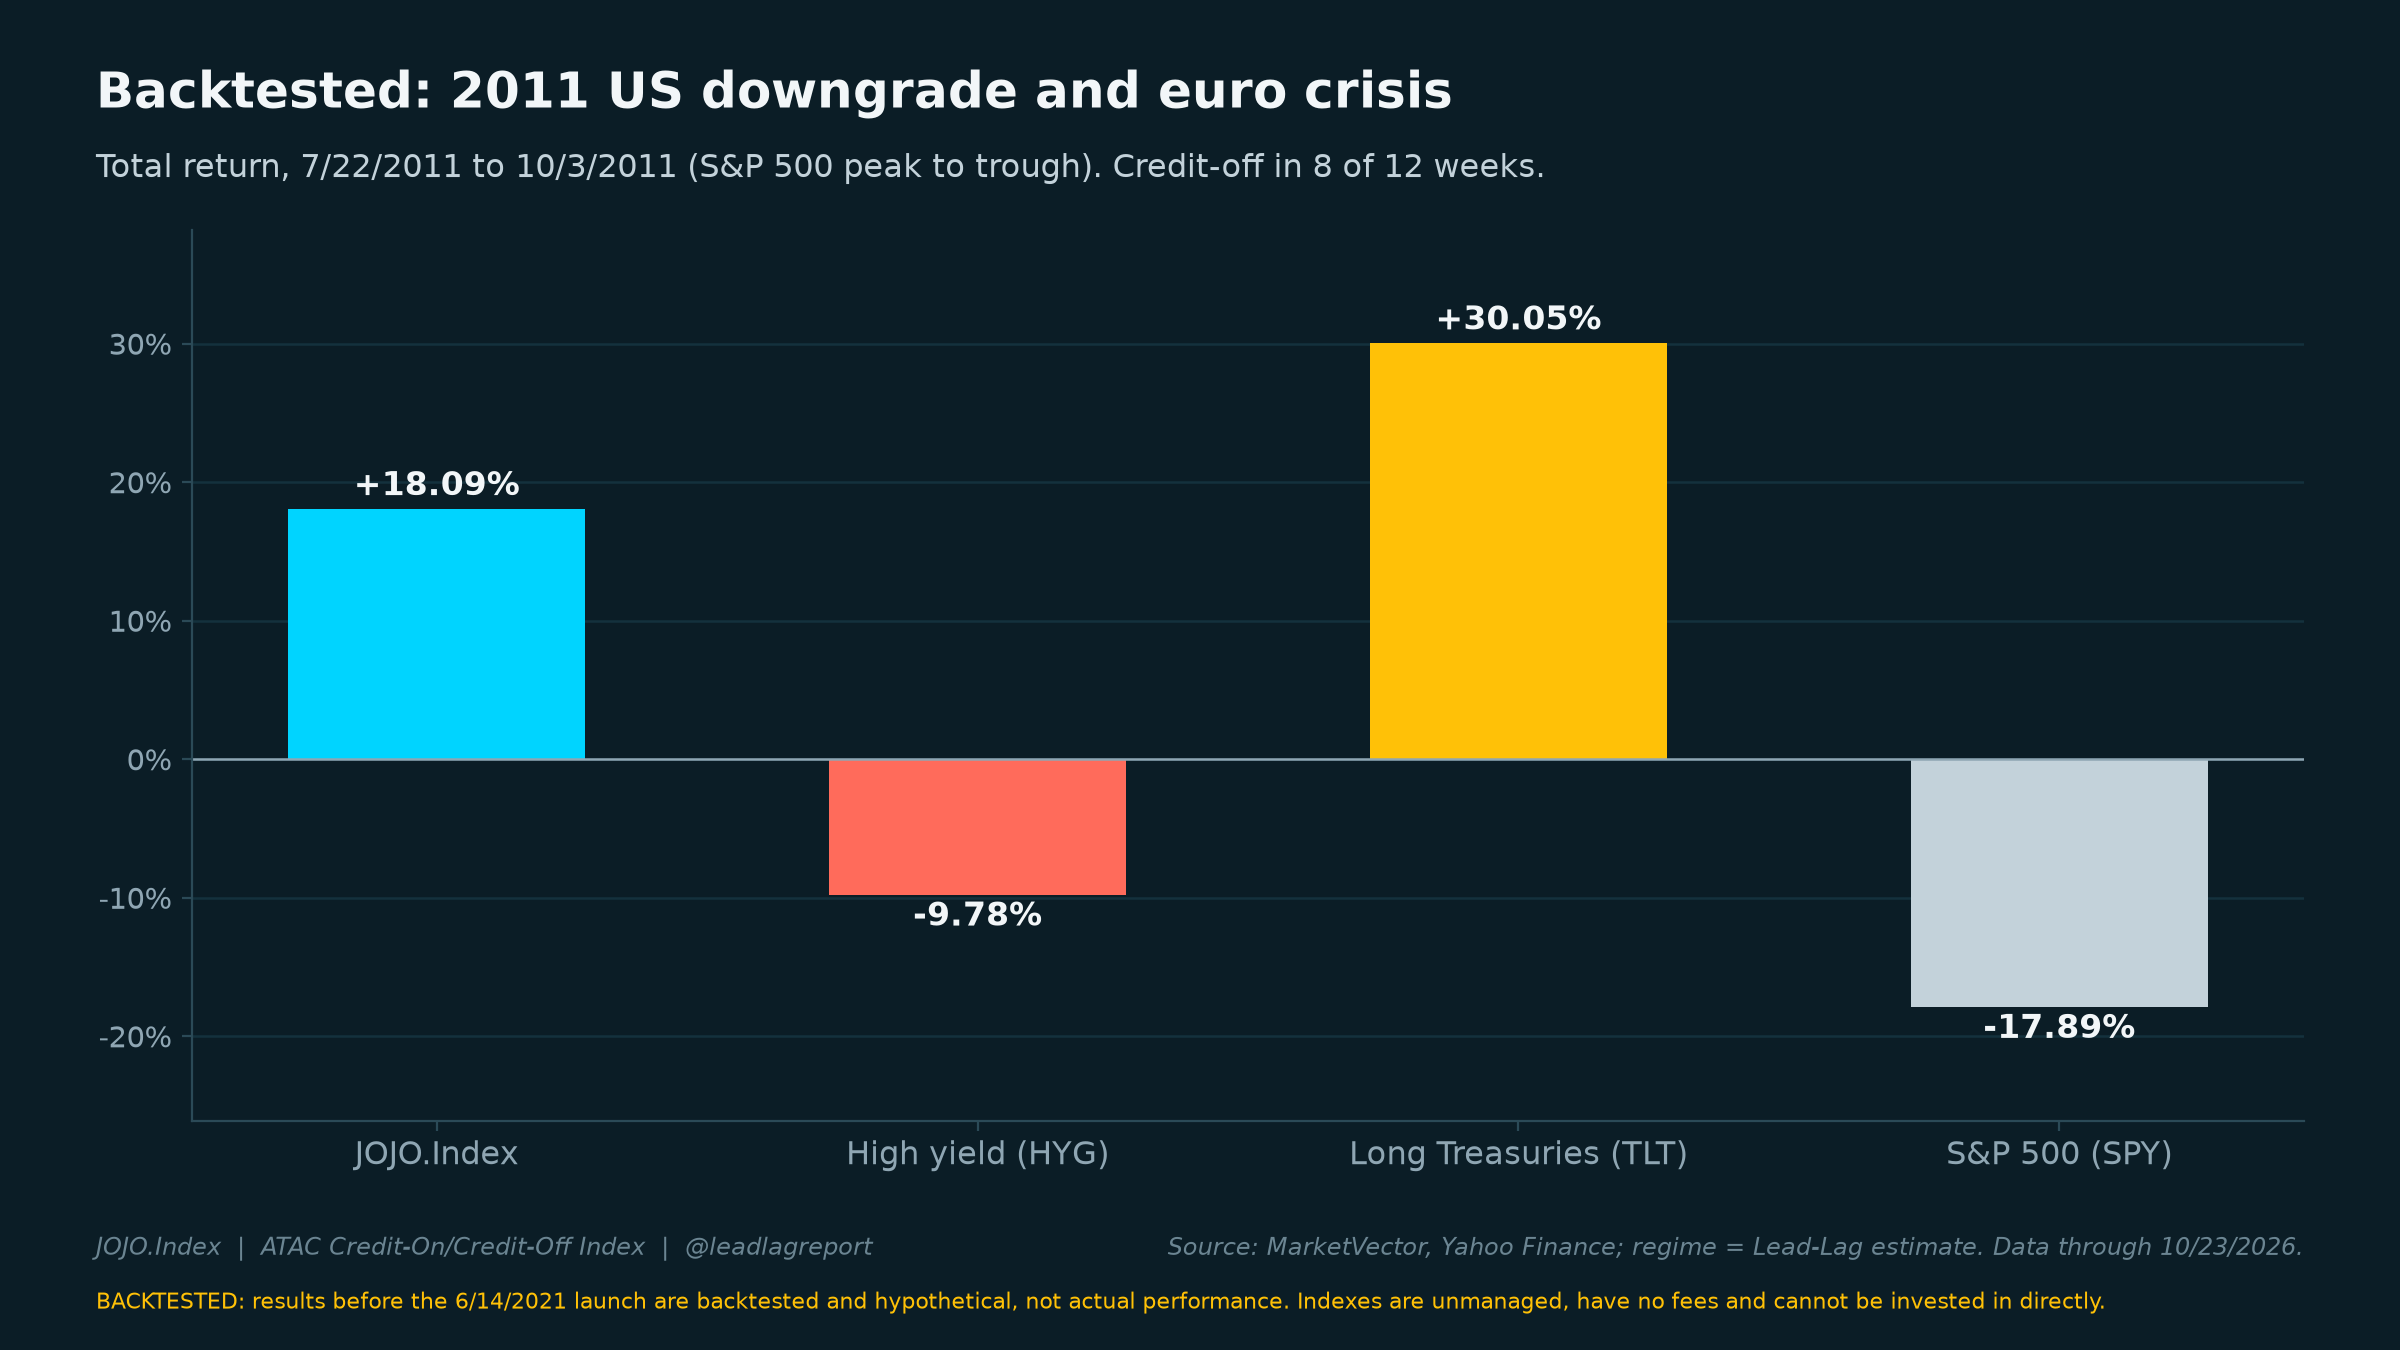
Backtested, 7/22/2011 to 10/3/2011, the S&P 500 peak to trough around the US downgrade and the euro crisis: the S&P 500 fell 17.89%. High yield fell 9.78%. The JOJO.Index gained 18.09%, credit-off in 8 of 12 weeks. These results are backtested and hypothetical; the index launched 6/14/2021.
The live scorecard
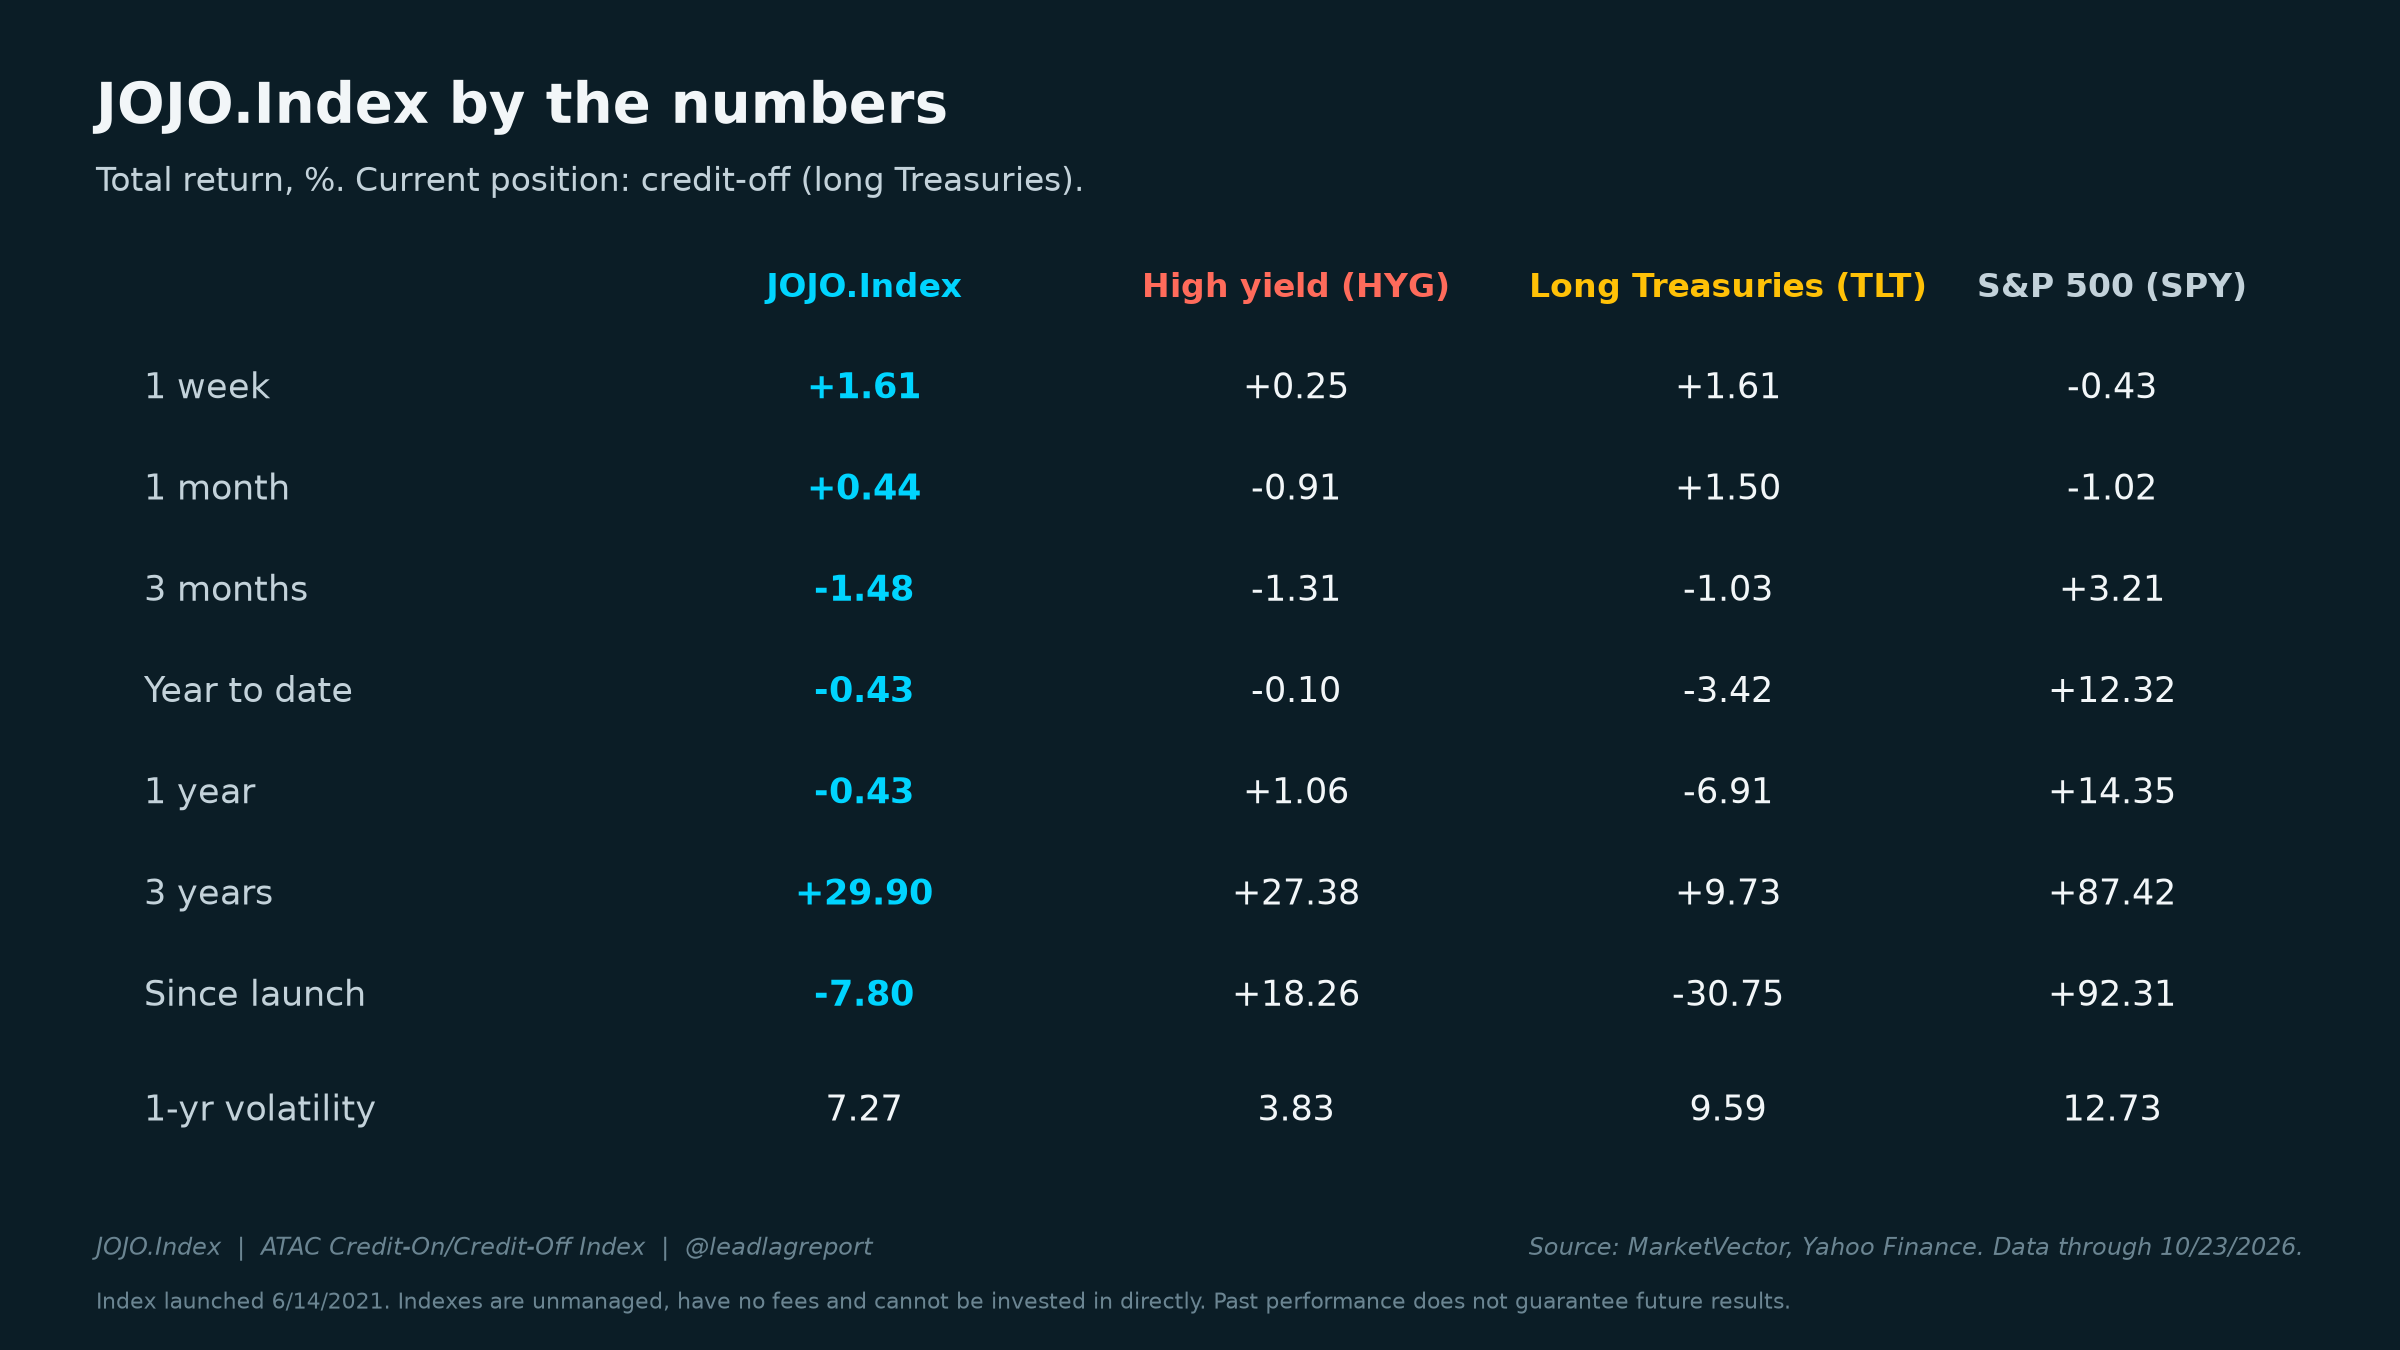
Live record, total return: 1 week +1.61%, 1 month +0.44%, year to date -0.43%, 3 years +29.9%, since the June 2021 launch -7.8%. The live years have been harder than the backtest, mostly because 2022 hit long Treasuries, the defensive sleeve, harder than it hit high yield. The full table is below, good and bad.
The JOJO.Index is the ATAC Credit-On/Credit-Off Index, administered by MarketVector, launched 6/14/2021. Results before launch are backtested and hypothetical, not actual performance. Indexes are unmanaged, have no fees and cannot be invested in directly. Past performance does not guarantee future results. Regime history is a Lead-Lag estimate from daily index returns. Sources: MarketVector, Yahoo Finance, ICE BofA via FRED. Not investment advice.
The Lead-Lag Report is provided by Lead-Lag Publishing, LLC. All opinions and views mentioned in this report constitute our judgments as of the date of writing and are subject to change at any time. Information within this material is not intended to be used as a primary basis for investment decisions and should also not be construed as advice meeting the particular investment needs of any individual investor. Trading signals produced by the Lead-Lag Report are independent of other services provided by Lead-Lag Publishing, LLC or its affiliates, and positioning of accounts under their management may differ. Please remember that investing involves risk, including loss of principal, and past performance may not be indicative of future results. Lead-Lag Publishing, LLC, its members, officers, directors and employees expressly disclaim all liability in respect to actions taken based on any or all of the information on this writing.