
High Yield Spotlight
40% Leverage, Asia-Pacific Bonds, A 15% Trailing Yield: Inside FAX
A 40-year-old CEF lending across Asia-Pacific at 40% leverage, marked at a wider-than-average discount.
CFA charterholder. Founder of Lead-Lag Media. Publisher of The Lead-Lag Report. 5x Dow & NAAIM Founders Award winner for research on intermarket signals.
High Yield Spotlight
A 40-year-old CEF lending across Asia-Pacific at 40% leverage, marked at a wider-than-average discount.
Closing Thoughts
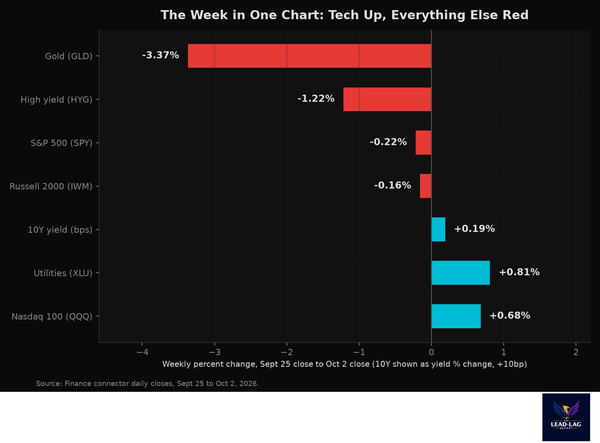
When the weakest jobs report of the year buys equities a rally and the bond market nothing at all, what exactly is the equity market rallying into?
Macro Observations
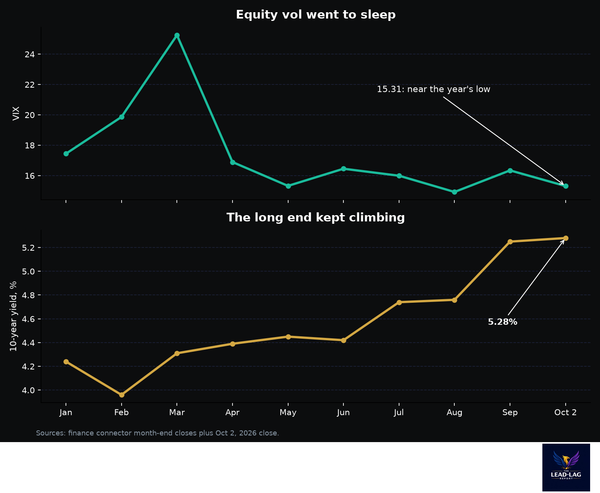
The VIX sleeps at 15.31 while the 10-year climbed 104 basis points this year and TLT fell 11.1 percent. Volatility is not a number, it is a location, and in 2026 the location is duration.
Book Release
The third edition of my father’s Intermarket Analysis and Investing is here. Read my foreword, and find the paperback and Kindle editions.
High Yield Spotlight
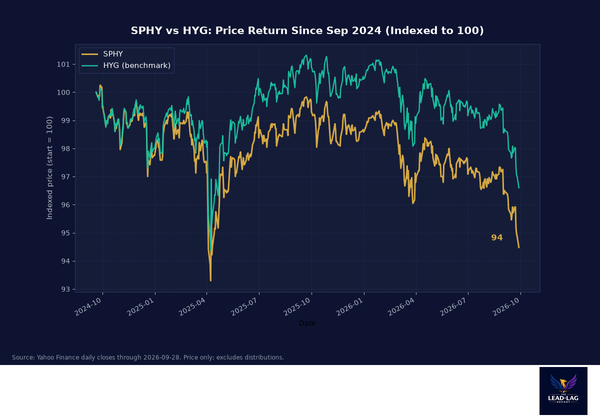
SPHY's 7.10% SEC yield at a 2.89-year duration for five basis points is the honest baseline for junk income.
Macro Observations
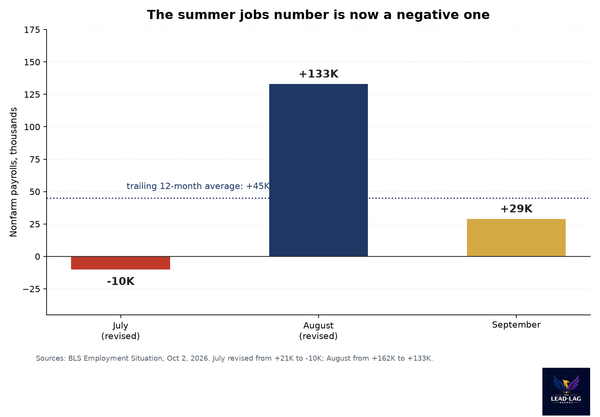
September payrolls missed by two thirds, July revised to negative 10,000, and stocks rallied while the 10-year still closed higher at 5.28 percent. Stocks and bonds disagreed about the same number.
High Yield Spotlight
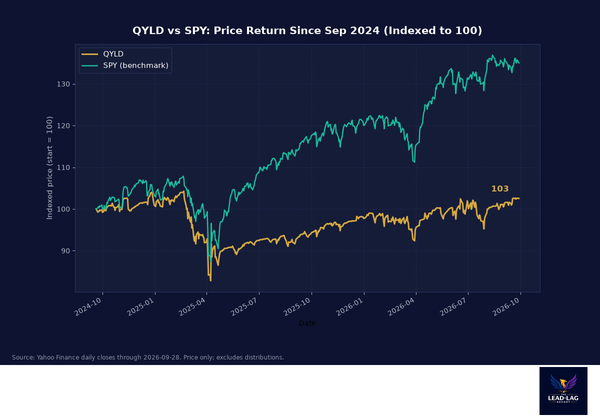
The widest distribution-to-SEC-yield gap I have covered: what QYLD's option premium machine actually sells.
High Yield Spotlight
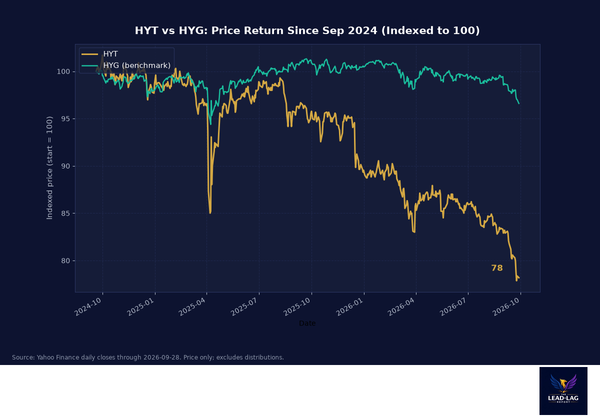
HYT pays 12% while its discount to NAV widened from -6.49% to -11.68%. Value entry or distribution warning.
Macro Observations
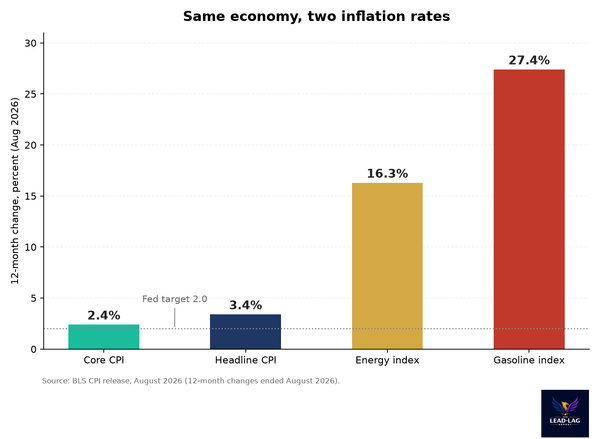
Core CPI sits at 2.4 percent, essentially at target. The headline gap is gasoline, up 27.4 percent on the year and over a third of August's entire monthly increase. The Fed hiked into it anyway.
High Yield Spotlight
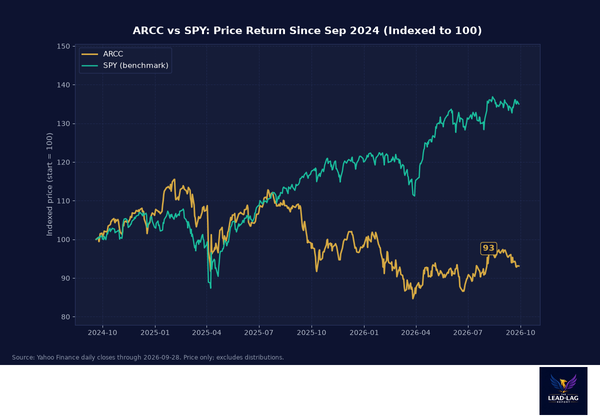
ARCC's $29.5 billion book pays $0.48 a quarter, but core EPS is $0.47 and NAV slipped to $19.59.
Macro Observations
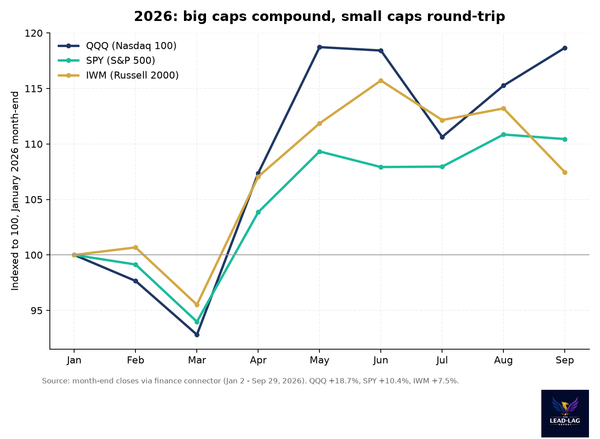
The 10-year climbed from 4.24 to 5.25 percent this year. Small caps already did the math: a -0.54 monthly correlation between rates and the Russell 2000, and an 11-point gap to the Nasdaq 100 since July.
Global View
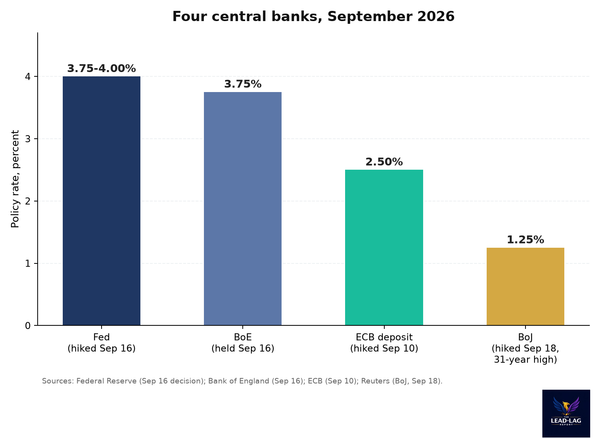
The Fed, the ECB and the BoJ all hiked in September, the BoE held, and China eased. The 10-year ends of the US, Germany and Japan all climbed anyway. The risk being priced is fiscal, not monetary.