Macro Observations
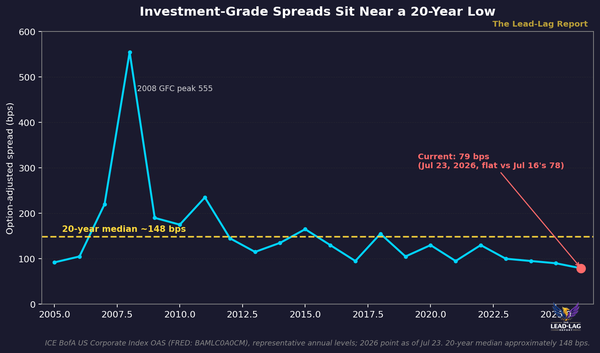
The AI Capex Bubble Won't Die From Demand. It'll Die From Spreads.
Capex Cycles Die From the Top of the Capital Stack. Everyone Is Watching the Wrong Number.
CFA charterholder. Founder of Lead-Lag Media. Publisher of The Lead-Lag Report. 5x Dow & NAAIM Founders Award winner for research on intermarket signals.
Macro Observations
Capex Cycles Die From the Top of the Capital Stack. Everyone Is Watching the Wrong Number.

High-Yield-Spotlight
PFLT yields 13% and trades at a 28% NAV discount -- the deepest of our BDC trilogy. The distribution was cut from $0.1025 to $0.08/mo, but NII now covers it at 104%. Is the bad news priced in, or is another cut coming? A full analysis of the risk/reward.

High-Yield-Spotlight
TRIN High Yield Spotlight. TRIN funds venture-backed companies through equipment loans and senior secured debt. Record originations, 32% NII growth, and $0.71 in spillover incom

High-Yield-Spotlight
AMLP High Yield Spotlight. The same midstream infrastructure that moves natural gas to AI data centers, without the K-1 tax headache. The catch is built into the structure itsel

High-Yield-Spotlight
GBAB High Yield Spotlight. GBAB holds taxable munis and investment-grade debt -- the exact portfolio that rises in price when interest rates fall. But 40.7% of its distributions
Global View
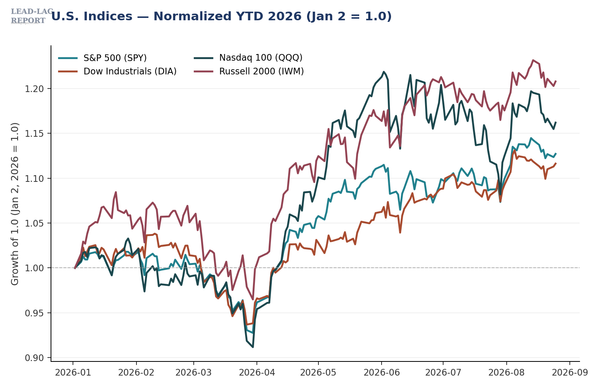
Gold's strongest close since January and Brent's supply-driven unwind are not the same trade — and copper says the growth scare is fake.
Leaders-Laggards
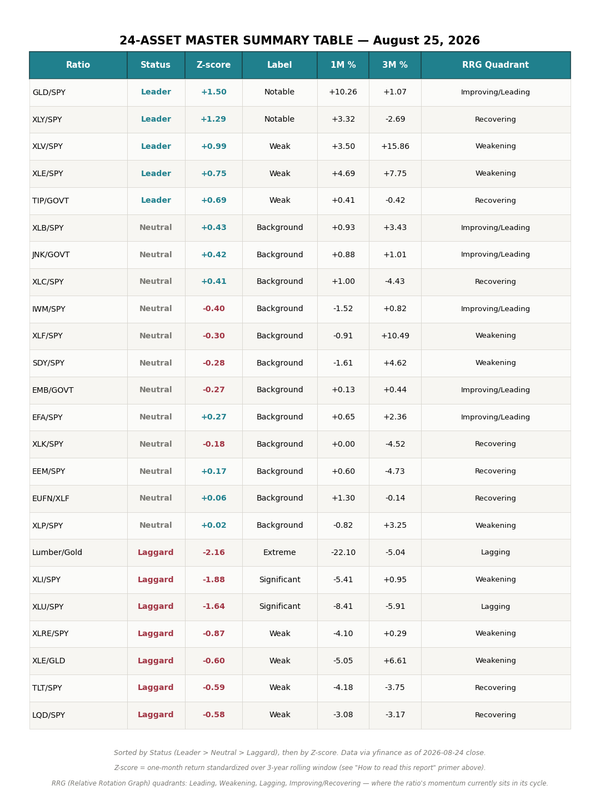
First Lumber/Gold Extreme reading in 3 years. XLI CRASHED to Significant Laggard. Gold Notable Leader. Late-cycle rotation widening.
Weekly Signals
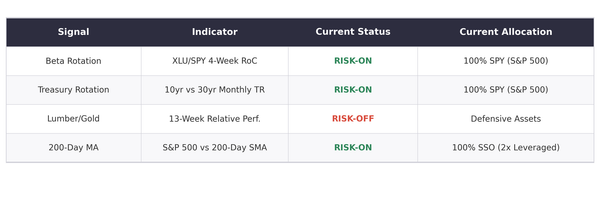
Three of four intermarket signals favor risk-on positioning this week. Lumber/Gold remains the lone defensive holdout.
Macro Observations
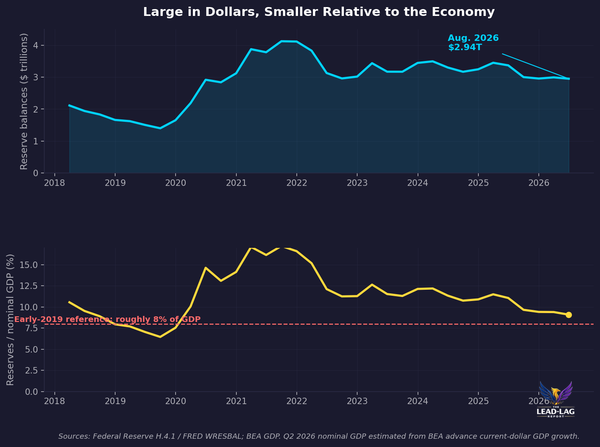
Reserves are large in dollars but thin relative to the system they must finance. SRF activation and repo spreads show the Fed's ample-reserves cushion is smaller than the headline balance implies.
Macro Observations
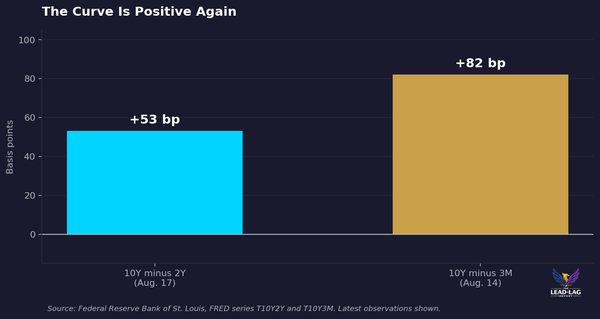
A positive slope is a funding condition, not proof that growth has absorbed the baton. The August 2026 curve is positive again, but the payroll and credit data have not yet confirmed the handoff.
Macro Observations
Credit reports are catching up to the payment pause, but the real macro hit arrives later

Macro Observations
New issuance can make the maturity schedule look safer while quietly transferring the problem into coupons, covenants, and weaker borrowers